Sep 06

M&A Litigation Support Services: Expert Financial Advisory for Complex Disputes

Arti Jain September 6, 2026

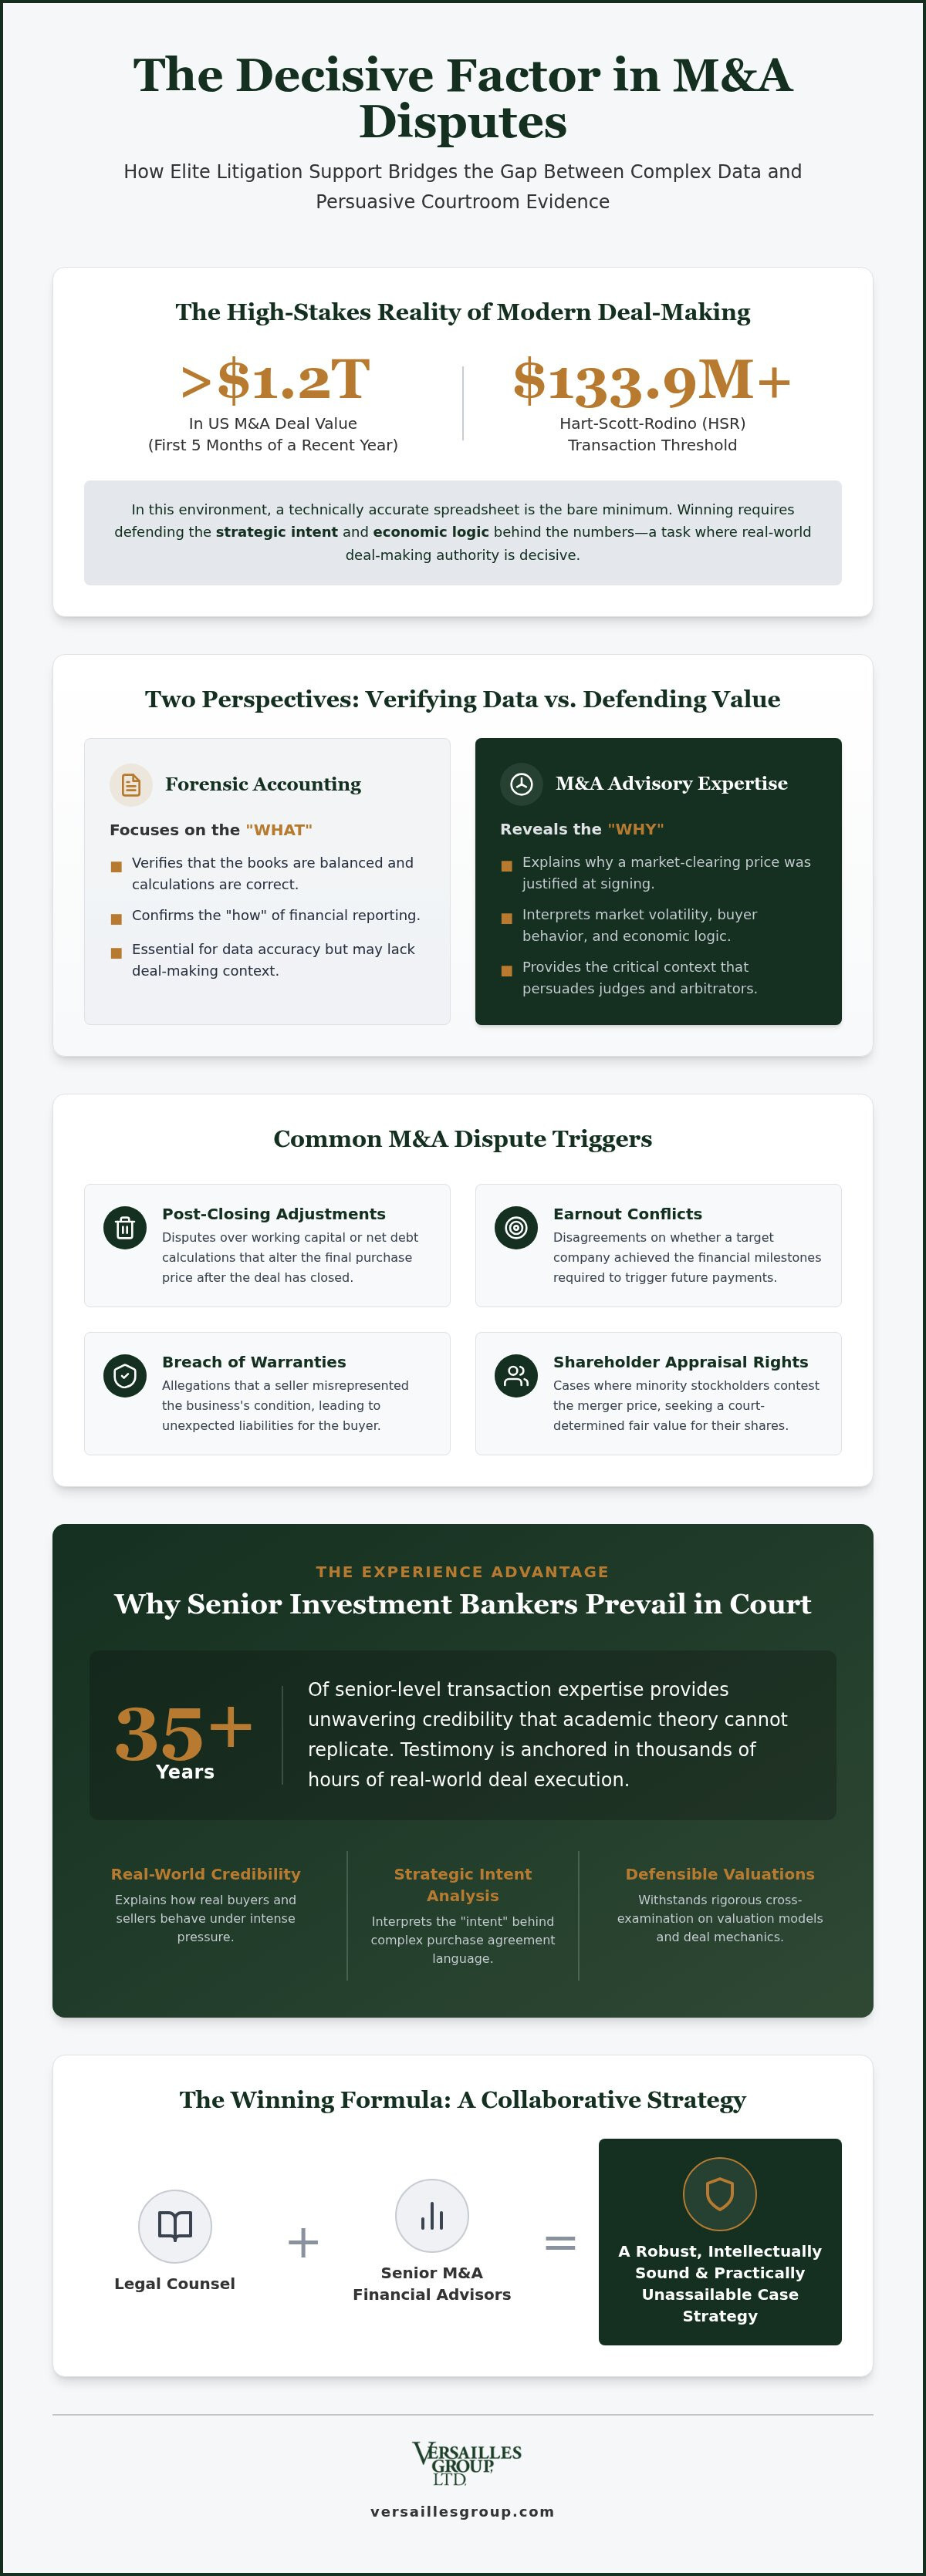
In the high-stakes arena of corporate disputes, a flawless spreadsheet is often the bare minimum required to survive, yet it's rarely enough to win. You likely recognize that when deal structures become sufficiently complex, the core truth often hides behind layers of sophisticated accounting and aggressive valuation models. It's a difficult reality where the most technically accurate argument can still fail if it lacks the weight of real-world deal-making authority. This is where elite M&A litigation support services become the deciding factor in the courtroom.

Discover how senior-level investment banking expertise provides the analytical depth and unwavering credibility necessary to withstand intense cross-examination and prevail in complex legal disputes. We'll examine the transition from raw data to robust financial evidence, the mechanics of a defensible valuation, and the strategic advantage of partnering with advisors who have spent decades at the negotiation table. By moving beyond simple calculations to reveal the strategic intent behind the numbers, you can build a legal strategy that is both intellectually sound and practically unassailable.

Key Takeaways

  • Understand how elite M&A litigation support services bridge the gap between complex transactional data and persuasive courtroom evidence.
  • Discover why real-world investment banking experience is essential for interpreting the strategic intent behind purchase agreements and valuation models.
  • Learn to identify financial "deal-breakers" early through specialized pre-litigation assessments and senior-level discovery support.
  • Explore how a collaborative workflow between legal counsel and financial advisors creates a more robust, unassailable case strategy.
  • Recognize the value of 35+ years of transaction expertise when defending high-stakes valuations under rigorous cross-examination.

Understanding the Scope of M&A Litigation Support Services

Litigation support in the context of Mergers and acquisitions (M&A) is the specialized bridge between high-stakes deal-making and the rigorous demands of the courtroom. While a transaction begins with the hope of synergy and growth, the reality of complex deal structures can lead to deep-seated disagreements. Effective M&A litigation support services don't simply provide data; they provide a narrative of financial truth backed by decades of transactional experience. In 2026, where US M&A deal values reached $1.2 trillion in just five months, the financial stakes of these disputes have never been higher.

The transition from deal advisory to dispute resolution requires a fundamental shift in perspective. During a deal, the focus is on negotiation and execution. In litigation, the focus turns to the defense of value and the interpretation of intent. This intersection of financial analysis and legal strategy is where senior-level expertise becomes indispensable. As transactions become more strategic and top-heavy, the underlying financial models require a level of scrutiny that standard consulting often misses. With the HSR size of transaction threshold rising to $133.9 million in 2026, even mid-sized disputes now involve the level of complexity once reserved for the largest corporate entities.

The Distinction Between Accounting and M&A Advisory

Forensic accounting is often the first tool legal teams reach for, yet it's only one piece of the puzzle. While an accountant can verify that the books are balanced, they may lack the context to explain why a specific market-clearing price was justified at the time of signing. M&A advisory brings a deal-maker's lens to the table. It involves understanding market volatility, buyer behavior, and the specific pressures of the middle market. This experience informs a more nuanced dispute analysis, allowing experts to explain not just the numbers, but the economic logic that drove the transaction in the first place. Understanding the "why" behind a valuation is often more persuasive to a judge than simply confirming the "how."

Common Scenarios Requiring Litigation Support

Disputes typically emerge when the post-closing reality fails to align with pre-closing expectations. These conflicts often center on specific contractual triggers or valuation gaps that were obscured during the rush to close. Common scenarios include:

  • Post-closing price adjustments: Disputes over working capital calculations or net debt levels that change the final purchase price.
  • Earnout conflicts: Disagreements over whether the target company achieved the financial milestones required to trigger additional payments, often complicated by AI-driven performance metrics.
  • Breach of representations and warranties: Allegations that a seller misrepresented the condition of the business, leading to unexpected liabilities for the buyer.
  • Shareholder appraisal rights: Cases where minority stockholders contest the merger price, seeking a court-determined fair value that reflects the company's true worth.

Why Investment Banking Expertise is Critical in Deal Disputes

While academic experts provide theoretical frameworks, they often lack the tactical intuition gained from decades at the negotiation table. In the context of Litigation in Mergers and Acquisitions, a judge isn't just looking for a math formula. They're looking for a clear explanation of how real buyers and sellers behave under intense pressure. Specialized M&A litigation support services bridge this gap by offering experts who have lived through the deal cycles they are now analyzing. This practical experience allows a senior advisor to interpret the "intent" behind a purchase agreement's language with a level of credibility that a pure academic cannot replicate. When a boutique partner with over 35 years of experience speaks, their testimony is anchored in thousands of hours of real-world execution, not just textbook scenarios.

Analyzing Deal Mechanics and Structure

Disputes often arise from the technical nuances of deal compensation or structure. For instance, interpreting the Lehman formula in a fee dispute requires more than just simple multiplication; it requires an understanding of standard industry practices and the specific expectations of middle-market participants. Whether evaluating a complex divestiture or the fairness of a private placement, a seasoned investment banker can decode these structures for a jury. They translate opaque financial jargon into a logical narrative of cause and effect. If you're facing a dispute over transaction mechanics, engaging a firm with senior-level advisory experience ensures that your defense is rooted in market reality rather than abstract theory. This level of high-touch involvement is particularly critical in the middle market, where deal terms are often bespoke and less standardized than in large-cap transactions.

Valuation Accuracy in High-Stakes Litigation

Standard Discounted Cash Flow (DCF) models are easily manipulated and frequently challenged in court. To provide a truly unassailable defense, an expert must look beyond the spreadsheet. Comparable transaction analysis, when performed by a practitioner who understands why those specific deals were struck, carries significantly more weight. This depth of analysis is critical for addressing "hindsight bias," where a plaintiff uses post-deal market shifts to claim a valuation was flawed at the time of closing. The effectiveness of M&A litigation support services often hinges on the expert’s ability to reconstruct the market sentiment of the closing date, proving that the valuation was fair based on the information available at the time. This methodical approach transforms a vulnerable model into a robust piece of evidence that can withstand the most aggressive cross-examination.

Core Components of Comprehensive M&A Litigation Support

Comprehensive M&A litigation support services involve a methodical deconstruction of the transaction from inception to dispute. It's not enough to simply react to legal filings; a proactive strategy begins with a rigorous pre-litigation assessment. This phase involves evaluating the economic viability of a claim before significant costs are incurred. By identifying the financial strengths and vulnerabilities early, counsel can determine whether a settlement or a full trial is the most strategic path forward. This initial clarity is essential for managing risk in the middle market, where the complexity of a deal often masks its underlying financial reality.

In the discovery phase, senior advisors identify the specific financial data points that define a deal’s history. This goes beyond standard ledger entries to include internal projections, board minutes, and correspondence that reveal the true valuation drivers. Once the data is secured, the focus shifts to quantifying damages. Whether the dispute involves lost value from a breach or an overpayment due to misrepresentation, the calculation must be grounded in market-clearing logic. Rebuttal analysis then serves as a critical final layer, where the expert identifies flaws in the opposing side's methodology, often exposing theoretical assumptions that don't hold up in practical deal-making scenarios.

Fairness Opinions as a Litigation Shield

A formal report from an independent advisor serves as a powerful deterrent to litigation. By providing Fairness Opinions during the deal process, boards of directors demonstrate they've met their fiduciary duties through senior-level oversight. These reports validate that the transaction terms are fair from a financial point of view, creating a documented record that's difficult to challenge post-closing. In the middle market, where transparency is often scrutinized, this preemptive step often prevents disputes from ever reaching the courtroom. It provides a steady hand and a clear audit trail for shareholders and regulators alike.

Expert Witness Testimony and Depositions

The transition from analytical support to the witness stand is where senior-level experience becomes a decisive advantage. During deposition and trial, the ability to maintain a sense of calm assurance under aggressive cross-examination is vital. Senior partners don't just provide answers; they provide credible authority. Preparation for these moments requires a high-touch approach, ensuring the expert is deeply familiar with every nuance of the case. This dedicated involvement ensures that the financial evidence is presented with the weight of institutional expertise, turning complex data into a clear, winning narrative that judges and juries can trust.
M&A litigation support services

Success in high-stakes disputes depends on a seamless partnership between legal counsel and financial advisors. It isn't enough for bankers to provide a static report; they must understand the specific legal theory of the case. By integrating M&A litigation support services at the earliest stages, counsel can identify "deal-breaker" financial issues that might otherwise remain buried until the trial phase. This early involvement ensures that the financial narrative is not just accurate but also legally relevant and capable of meeting the Daubert standard for admissibility in federal and state courts. A well-constructed strategy ensures that the data doesn't just sit in a spreadsheet; it actively supports the overarching legal argument.

Strategic Document Review and Data Extraction

An experienced investment banker approaches a Confidential Information Memorandum (CIM) or Offering Memorandum with a different eye than a legal team. They look for the subtle cues in financial disclosures that suggest aggressive revenue recognition or understated liabilities. By leveraging historical deal data from middle-market transactions dating back to 1987, a senior advisor provides the context necessary to uncover discrepancies that a standard audit might overlook. This methodical extraction of data ensures that every piece of evidence is anchored in the reality of how deals are actually marketed and sold. It moves beyond checking boxes to understanding the commercial pressures that existed during the deal's formation.

Refining the Damage Model

Once the data is extracted, the financial model must be iteratively refined to align with specific legal theories of recovery. This is a deliberate process. It requires testing the sensitivity of valuation inputs to ensure that the final damage figure is both robust and defensible. If a single variable change collapses the entire model, the evidence won't survive cross-examination. Senior advisors focus on creating models that reflect the actual behavior of middle-market buyers and sellers. Clear, visual exhibits are then developed to translate these complex calculations into a format that a judge or jury can easily digest. If you require a partner who can provide this level of senior-level precision and quiet confidence, contact Versailles Group for expert witness and M&A litigation support services. This high-touch approach ensures that your legal strategy is backed by a narrative of financial excellence.

Versailles Group: Senior-Level Advisory for High-Stakes M&A Litigation

Since its founding in 1987, Versailles Group has operated as a steady hand in the volatile world of corporate finance. For over 35 years, our firm has provided the specialized M&A litigation support services required to resolve institutional-grade challenges with the agility of a boutique partner. In high-stakes legal disputes, the depth of an expert’s experience is often the primary factor that determines the credibility of a financial defense. We prioritize quality over volume, ensuring that every case receives the sophisticated analysis and quiet confidence that only a seasoned deal-maker can provide. This commitment to elite standards makes us a trusted alternative to larger, less personal institutions.

Senior-level attention isn't just a preference in litigation; it's a non-negotiable requirement for success. When a case reaches the deposition or trial phase, the opposing counsel will look for any gap in the expert's understanding of the transaction. At Versailles Group, we don't delegate critical analysis to junior associates. Our senior advisors are deeply involved in every aspect of the case, from the initial document review to the final courtroom testimony. This high-touch approach ensures that our findings are grounded in decades of real-world experience, providing a level of security and prestige that is essential for defending complex middle-market deal structures.

The Value of a Boutique Partner

Choosing a boutique firm for M&A litigation support services offers distinct strategic advantages that larger firms often struggle to replicate. Clients benefit from direct access to firm leadership, ensuring that every strategic decision is informed by an advisor who understands the nuances of the case. This structure allows for:

  • Agile response times: We move quickly to meet tight legal deadlines, providing the responsiveness required in fast-moving litigation.
  • Bespoke strategies: We avoid one-size-fits-all templates, tailoring our financial models to the specific middle-market complexities of your dispute.
  • Unwavering discretion: We value the sensitive nature of M&A disputes, maintaining the highest levels of confidentiality throughout the engagement.

Engagement and Next Steps

Engaging Versailles Group begins with a focused, confidential discussion to understand the specific objectives of your case. During an initial consultation, our senior advisors conduct a preliminary assessment of the financial claims to determine case viability. This methodical approach ensures that we only move forward when we can provide a clear, defensible path toward a winning legal strategy. Whether your dispute involves Fairness Opinions, divestitures, or private placements, our firm provides the institutional-grade expertise necessary to prevail. To discuss how our senior-level involvement can strengthen your litigation position, contact our advisors for a private consultation.

Securing Your Strategy with Elite Financial Authority

Prevailing in a high-stakes corporate dispute requires more than just technical accuracy; it demands the credibility of a seasoned practitioner. We've explored how senior-level investment banking expertise transforms complex data into persuasive evidence, ensuring that your legal strategy is anchored in market reality. By prioritizing deep analytical rigor and senior involvement, you ensure that every valuation model and damage calculation can withstand the intense scrutiny of the courtroom. Effective M&A litigation support services bridge the gap between opaque deal structures and the clarity required for a winning verdict.

Established in 1987, Versailles Group provides senior-level involvement in every engagement across domestic and international markets. Our firm brings a boutique focus to institutional-grade challenges, prioritizing quality and precision above all else. Contact Versailles Group for Senior-Level M&A Litigation Support to ensure your case is backed by elite standards and decades of transaction expertise. With a dedicated partner by your side, you can approach even the most complex disputes with quiet confidence and strategic clarity.

Frequently Asked Questions

What is the difference between an M&A expert witness and litigation support?

Litigation support is the broad process of discovery, document review, and damage modeling, while an expert witness provides formal testimony in court or deposition. Support often begins months before an expert is identified to testify. It involves identifying discrepancies in financial disclosures and building the technical foundation that the expert witness eventually defends under oath. Both roles require deep transactional experience to be effective in complex corporate disputes.

When should a legal team engage an M&A financial advisor in a dispute?

A legal team should engage a financial advisor as early as the pre-litigation phase to assess the economic viability of the claim. Waiting until the discovery period often results in missed opportunities to identify critical financial data or deal-breaker issues. Early involvement allows the advisor to help shape the legal theory of recovery based on realistic market behavior, ensuring the case is grounded in financial truth from the start.

How are fees typically structured for M&A litigation support services?

Fees for M&A litigation support services are typically structured on an hourly or project basis, depending on the complexity and scope of the engagement. Unlike transaction advisory, which often relies on success fees, litigation support requires compensation for the time spent on research, reporting, and deposition. This structure ensures the advisor's independence and objectivity, which are vital for maintaining credibility when presenting findings to a judge or jury in a high-stakes dispute.

Can an investment banker help with post-closing earnout disputes?

Yes, investment bankers are essential for resolving earnout disputes because they understand the commercial intent behind the original performance metrics. They analyze whether the buyer's post-closing actions unfairly impacted the target company's ability to reach financial milestones. By reconstructing the deal's economic logic, a senior advisor can determine if a breach occurred or if the shortfall resulted from broader market shifts, providing a clear narrative for settlement or trial.

What role does a fairness opinion play in M&A litigation?

A fairness opinion serves as a formal validation that the financial terms of a transaction were fair to shareholders at the time of closing. In litigation, these reports act as a shield for boards of directors, demonstrating that they fulfilled their fiduciary duties through senior-level oversight. If a transaction is challenged post-closing, the contemporaneous fairness opinion provides a documented audit trail that is much harder for plaintiffs to contest than retrospective analysis.

Why is middle-market experience important for litigation support?

Middle-market transactions often involve bespoke deal structures and private placements that don't follow the standardized templates of large-cap deals. An advisor with specific middle-market experience understands the nuances of working capital adjustments and closely held company valuations. This specialized knowledge is critical for identifying discrepancies in financial disclosures that a generalist firm might overlook, ensuring that the litigation strategy reflects the actual market environment of the target company.

How does an M&A expert calculate damages in a breach of contract case?

An expert calculates damages by comparing the "but-for" value of the business with its actual value following the breach. This process involves sophisticated modeling that accounts for lost synergies, diminished growth prospects, and unfulfilled representations. By using M&A litigation support services, counsel can ensure these calculations are backed by comparable transaction data and market-clearing logic rather than just theoretical projections, making the damage model far more defensible during cross-examination.

Does Versailles Group provide support for both plaintiff and defense counsel?

Versailles Group provides senior-level advisory and expert witness services for both plaintiff and defense counsel across domestic and international markets. The firm's focus is on providing objective, institutional-grade analysis that withstands rigorous legal scrutiny regardless of the side we represent. Since 1987, our senior advisors have maintained a commitment to precision and discretion, ensuring that every engagement is handled with the quiet confidence required for high-stakes corporate disputes.
Sep 06

Middle Market Company Valuation: Strategic Frameworks for 2026

Arti Jain September 6, 2026

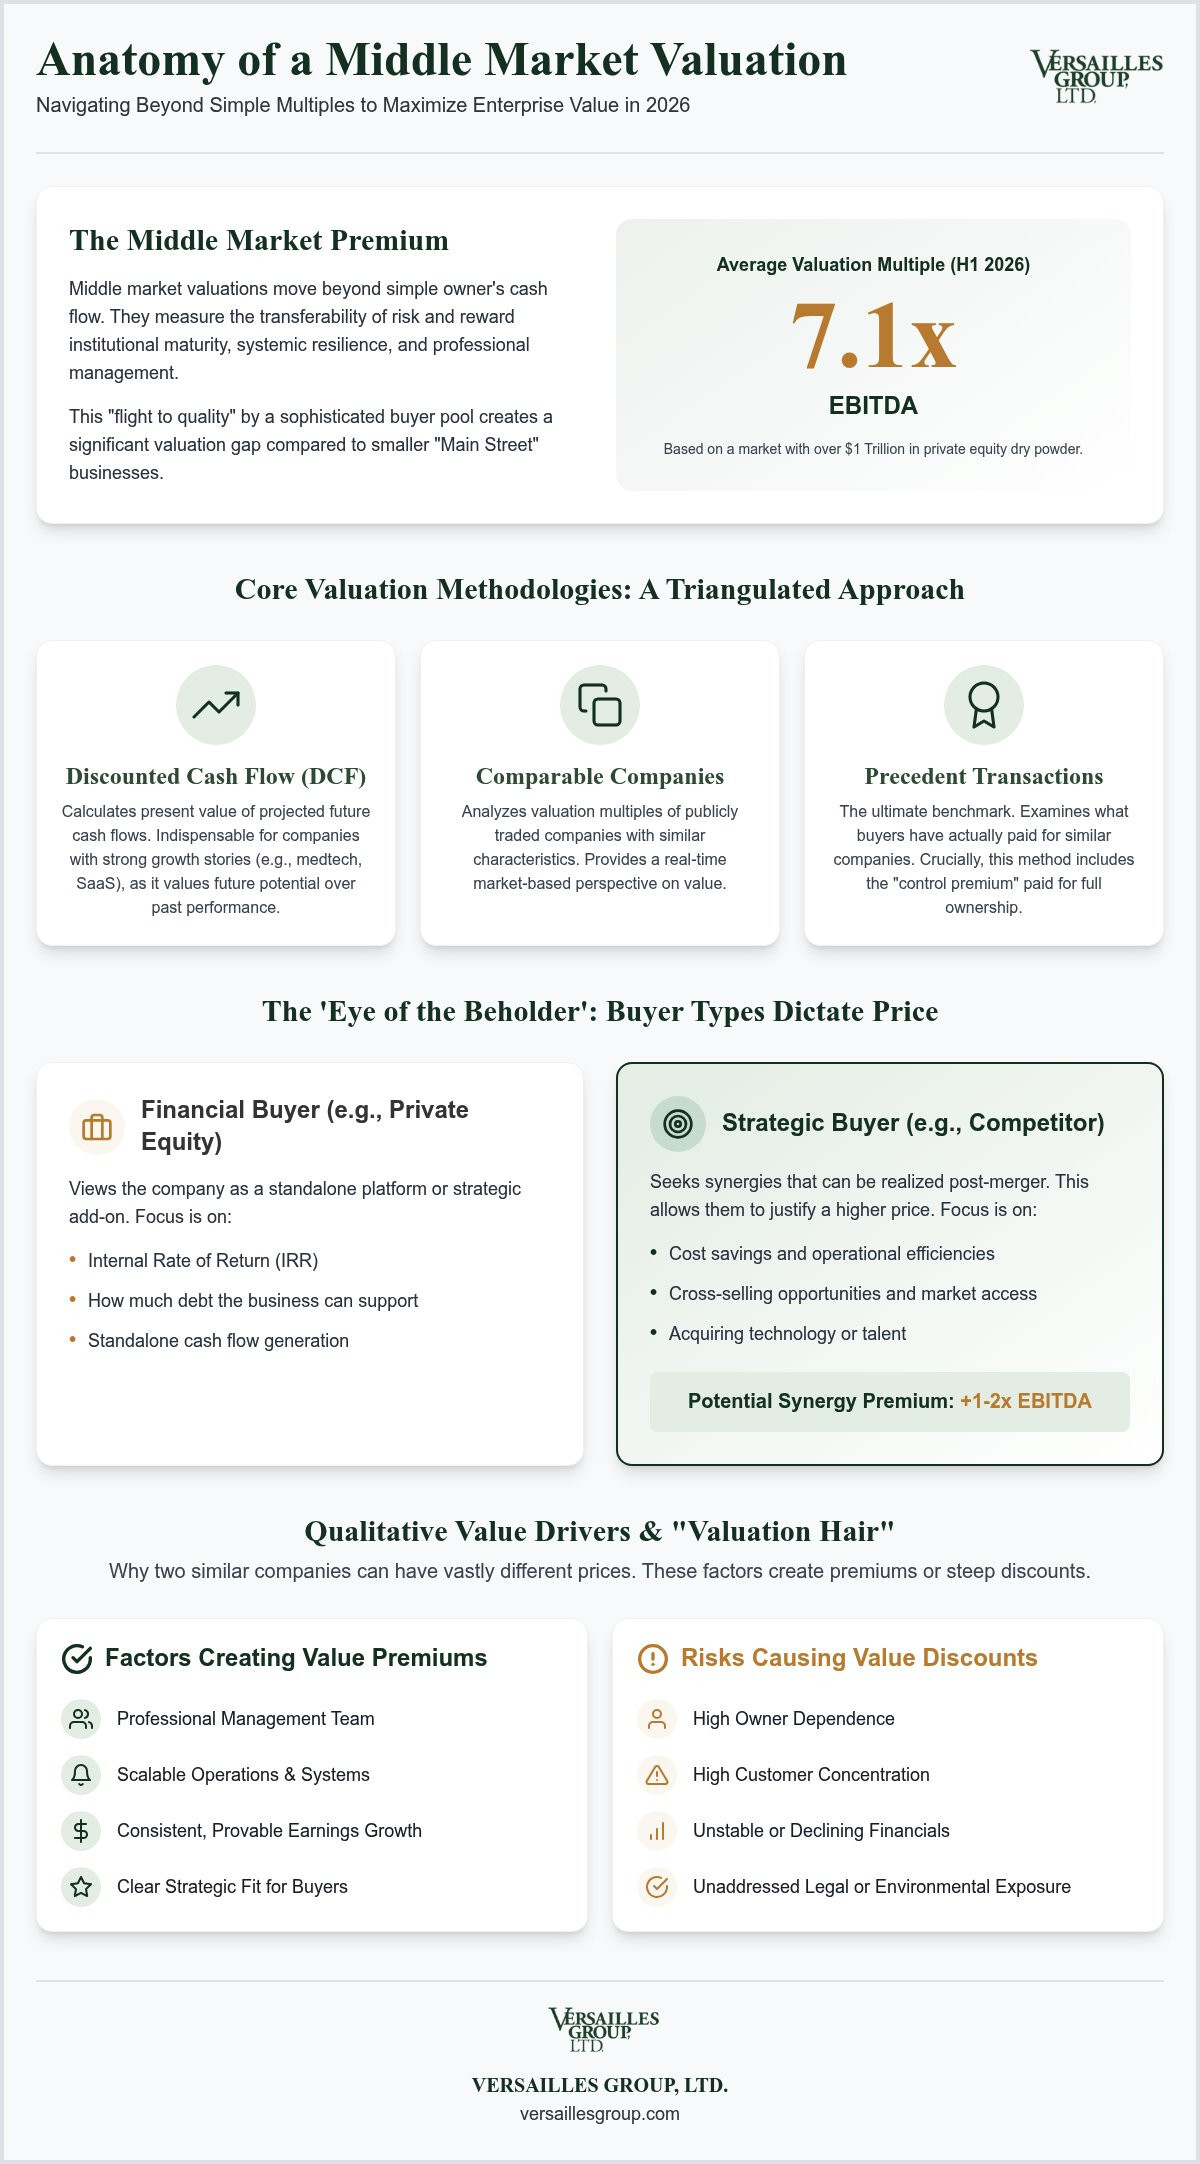
In the middle market, valuation is a measurement of risk transferability, not just a multiple of past earnings. While the average middle market company valuation hovered at 7.1x EBITDA during the first half of 2026, relying solely on broad averages often leads to a mismatch between internal expectations and actual market offers. You likely feel the tension between what your financial statements say and what a strategic buyer is willing to pay. This gap isn't just about the math; it's about how well your firm's stability and growth potential are articulated to a disciplined buyer pool.

It's frustrating to see differing results from various valuation models or to worry that poor positioning might leave significant money on the table. This guide provides the clarity you need to master the sophisticated methodologies and qualitative drivers that dictate enterprise value in the current M&A environment. We'll examine the technical mechanics behind the deal, explore actionable strategies to enhance your company's worth before a sale, and establish a rigorous framework to defend your price during high-stakes negotiations.

Key Takeaways

  • Understand why Enterprise Value (EV) serves as the definitive metric for sophisticated M&A, moving beyond the simplistic multiples used in Main Street transactions.
  • Identify how qualitative factors, such as owner dependence and customer concentration, can significantly influence a middle market company valuation by either creating a premium or a steep discount.
  • Learn to proactively address valuation "hair," including legal exposure and unstable financial performance, to prevent these risks from devaluing your firm during due diligence.
  • Recognize the strategic importance of a Fairness Opinion as a critical fiduciary shield for boards of directors navigating complex divestitures in 2026.
  • Equip yourself with a structured framework to defend your asking price and bridge the gap between internal expectations and the buyer's disciplined math.

Defining Middle Market Company Valuation: The Strategic Intersection

Middle market company valuation differs fundamentally from the valuation of smaller "Main Street" businesses. While a local shop might sell based on a simple multiple of the owner's cash flow, mid-sized firms operate with institutional maturity. This scale reduces buyer risk, creating a "Middle Market Premium" where multiples naturally inflate as a company proves its systemic resilience. In the 2026 market, where the average multiple is approximately 7.1x EBITDA, investors prioritize entities with professional management teams and scalable operations. The current environment is defined by a flight to quality. While capital remains abundant, with private equity dry powder exceeding $1 trillion, buyers are increasingly selective. They favor companies that demonstrate consistent earnings growth and a clear strategic fit over those with volatile performance.

Revenue vs. Enterprise Value: Understanding the Difference

A precise middle market company valuation requires moving beyond top-line figures. Revenue multiples are often a trap for mid-sized firms. Unless you are in a high-growth technology sector, buyers focus on the bottom line and the sustainability of cash flows. Most transactions are structured as "cash-free, debt-free," meaning the seller keeps the cash and pays off all debt at the time of closing. This arrangement requires a clear understanding of normalized working capital to avoid disputes during the final stages of the deal. Enterprise Value is the theoretical purchase price of a company including its debt and excluding its cash. By focusing on this metric, advisors strip away the noise of a company's specific financing choices to reveal its true operational worth.

The 'Eye of the Beholder' Concept in Valuation

The type of buyer you attract dictates the final number. Financial buyers, such as private equity firms, focus on internal rates of return and how much debt the business can support. They value the company as a standalone platform or a strategic add-on acquisition. Strategic buyers, often competitors or adjacent players, look for synergies that can be realized after the merger. These synergies, such as cost savings, cross-selling opportunities, or expanded market access, often allow strategic buyers to offer a premium of 1-2x EBITDA over financial bids. Identifying the right buyer pool is a strategic necessity to maximize the final exit price, as different bidders will weigh your company's assets through vastly different lenses.

Core Valuation Methodologies: DCF, Comps, and Precedents

A robust middle market company valuation isn't the product of a single formula. It's a triangulation of distinct methodologies that each offer a different perspective on risk and reward. Sophisticated advisors don't rely on a static number; they build a valuation range based on the quality of available data and the specific objectives of the seller. By combining the Income Approach with the Market Approach, you create a comprehensive financial narrative that can withstand the scrutiny of a buyer's due diligence team. This methodical process transforms abstract expectations into a defensible price that reflects both historical performance and future potential.

Precedent transactions often serve as the ultimate benchmark in middle market negotiations. This model examines what actual buyers have paid for similar companies in recent years. Unlike public market comparisons, precedent data includes the "control premium" that a buyer pays to gain full ownership of an entity. It's essential to adjust these historical figures for the specific market conditions of 2026, ensuring that the benchmark remains relevant to the current interest rate environment and capital availability.

Discounted Cash Flow (DCF): Modeling Future Potential

The DCF model is indispensable for firms with unique growth stories, such as those in medtech or specialized software. It calculates the present value of all projected future cash flows, providing a look at what the business is worth based on its trajectory rather than its past. In 2026, selecting the right discount rate is critical. This rate, known as the Weighted Average Cost of Capital (WACC), must accurately reflect the firm's specific risk profile and the cost of debt. A significant portion of a DCF valuation often rests in the Terminal Value, which represents the company's worth beyond the explicit forecast period. If your business is scaling rapidly, a DCF allows you to argue for a valuation that captures the value you've yet to realize.

Comparable Transaction Analysis: Real-World Benchmarking

To achieve a precise middle market company valuation, you must identify true peers. This goes beyond simple industry codes; you need to find companies with similar business models, recurring revenue streams, and margin profiles. Once peers are identified, the next step is normalizing earnings through EBITDA adjustments. These "add-backs" identify one-time expenses, excessive owner compensation, or non-operating costs that won't continue under new ownership. These adjustments are vital for revealing the true earning power of the asset. For boards of directors who need to validate these figures for shareholders, obtaining a Fairness Opinion serves as a vital fiduciary shield, ensuring the proposed deal is equitable from a financial perspective.

Qualitative Value Drivers: Why Two Similar Companies Have Different Prices

Financial statements provide the foundation for a middle market company valuation, yet they rarely tell the complete story. Two firms with identical EBITDA and growth rates can command drastically different multiples based on their underlying operational risks and strategic moats. Buyers in 2026 are increasingly discerning, looking past the spreadsheets to evaluate how easily a business can be integrated and scaled. A premium is often awarded to companies that demonstrate institutional maturity, while those mired in founder-led chaos face significant discounts.

One of the most common value detractors is owner dependence. If the founder is the primary salesperson, the chief engineer, and the key relationship holder, the business lacks transferability. Buyers view this as a high-risk investment; they aren't just buying cash flow, they're buying a machine that must run without its original architect. Conversely, a management premium is applied when a robust second-tier leadership team is already in place. Having capable VPs and directors allows a buyer to focus on growth rather than day-to-day survival.

Customer concentration remains a hidden risk that can destroy 20-30% of a firm's value instantly. If a single client accounts for more than 15-20% of total revenue, the business is essentially a captive entity. A single contract termination could jeopardize the entire company's solvency. To defend a high valuation, firms must show a diversified client base and proprietary intellectual property that creates high switching costs for customers, effectively building a moat around their market share.

Revenue Quality and Predictability

Not all revenue is created equal. Sophisticated investors distinguish between recurring revenue, which is contractually guaranteed, and re-occurring revenue, which relies on habitual repeat purchases. Contractual stickiness provides a level of predictability that justifies higher leverage and lower risk profiles. A $10M company with 90% recurring revenue is often worth more than a $20M company with one-off sales. Retention rates are a vital metric here; showing that clients consistently renew their agreements is a powerful argument for a premium multiple during a middle market company valuation.

Operational Infrastructure and Systems

The transition from a private business to an institutional asset requires rigorous operational infrastructure. Buyers look for institutional-grade financial reporting and modern ERP systems that provide real-time visibility into the business. In 2026, supply chain resilience has become a critical valuation factor. Firms that can prove they have diversified sourcing and localized contingencies are viewed as safer bets in a volatile global market. Finally, maintaining flawless regulatory compliance prevents the need for expensive clean-up efforts during due diligence, which can otherwise lead to last-minute price re-negotiations or "hair" on the deal.

Middle market company valuation

Identifying Valuation 'Hair': Risks That Depress Middle Market Prices

In a competitive M&A environment, "hair" refers to the operational and financial complications that erode a firm's perceived stability. Investors are particularly wary of catching a falling knife. If your EBITDA shows a downward trend in the quarters leading up to a sale, buyers will price in a margin of safety that often exceeds the actual financial decline. This perceived risk directly impacts a middle market company valuation, as buyers seek to protect their internal rate of return against further volatility. Beyond performance, pending litigation or environmental liabilities act as a significant weight on the deal, often requiring substantial escrows that tie up your liquidity for years after the transaction closes.

Capital expenditure requirements also play a pivotal role in price adjustments. If a business has neglected its equipment or technology, a buyer will view this deferred maintenance as an immediate liability. They'll likely demand a dollar-for-dollar reduction in the enterprise value to fund these necessary upgrades. Timing your exit is equally critical. Selling during a valuation trough in a cyclical industry can result in millions of dollars in lost equity. To ensure your board navigates these complexities with a clear fiduciary shield, consider engaging experts for Fairness Opinions to validate the equity of the final offer.

The Impact of Customer Concentration

Advisors often point to the 20/50 Rule as a threshold for concern. When a single customer accounts for 20% of revenue, or your top three clients represent over 50%, the risk profile of the business shifts. Buyers use this concentration to negotiate aggressive earnouts. Instead of receiving the full purchase price at closing, a portion of your payout becomes contingent on those specific customers remaining with the firm. Mitigating this risk requires a proactive strategy to diversify the client base or secure long-term, transferable contracts well before the sale process begins.

Working Capital and Deal Structure

The headline price on a Letter of Intent is rarely the walk-away price that hits your bank account. A primary driver of this discrepancy is the working capital peg. This figure represents the normal amount of capital required to operate the business, and if your actual working capital at the time of closing is below this peg, the purchase price is adjusted downward. The structure of the sale, whether it's a stock or asset transaction, also creates a tax-adjusted valuation reality. While buyers prefer asset sales for the tax step-up, sellers often face higher tax burdens that can significantly reduce their net proceeds. Understanding these mechanics is essential for defending your price during the final stages of a middle market company valuation.

The Strategic Advisor's Role in Navigating the Valuation Gap

A professional valuation serves as the anchor for the entire M&A lifecycle. Without this foundation, sellers risk entering the market with unrealistic expectations, while buyers may overlook the intrinsic value of a well-run operation. The advisor's primary objective is to bridge the psychological and mathematical divide between a seller's desired price and a buyer's calculated offer. In the complex landscape of 2026, this requires more than just running models; it demands a deep understanding of market sentiment and institutional capital flows. By grounding the process in objective data, a strategic partner ensures that the negotiation remains focused on value rather than emotion.

Choosing the right partner is a strategic decision in itself. Large institutional banks often delegate middle-market mandates to junior associates who lack the experience to navigate nuanced negotiations or complex deal structures. In contrast, the boutique model prioritizes senior-level attention at every stage of the process. This ensures that seasoned experts are the ones defending your valuation in the boardroom and during due diligence. Since 1987, Versailles Group has operated on this principle, providing the high-touch advisory needed to handle institutional-grade challenges with the agility of a specialized partner.

Fiduciary Duty and Fairness Opinions

For boards of directors, the stakes of a divestiture extend beyond the final purchase price. They have a legal and ethical obligation to ensure that a transaction is fair to all shareholders. A formal fairness opinion provides an independent, unbiased assessment that serves as a critical fiduciary shield. These assessments are particularly vital in 2026 to prevent shareholder litigation that can arise from perceived conflicts of interest or undervalued assets. By providing a rigorous, third-party validation of the deal terms, independent advisors help boards fulfill their duties with confidence and discretion. This independent oversight is often the difference between a smooth closing and a contested transaction.

Positioning the Story to Maximize the Multiple

Maximizing a middle market company valuation requires a blend of financial rigor and narrative strategy. It isn't enough to present historical data; you must translate qualitative strengths into quantitative financial models that buyers can justify to their investment committees. Creating competitive tension through a structured process is the most effective way to drive up market value. When multiple qualified bidders are at the table, the leverage shifts back to the seller, allowing for more favorable terms and higher multiples. If you're preparing for a transaction, you should contact Versailles Group for a confidential valuation assessment to begin establishing your strategic framework.

Securing Your Strategic Position in 2026

Success in the current M&A landscape requires a move beyond static multiples and towards a rigorous understanding of risk transferability. A precise middle market company valuation is built on the intersection of technical financial modeling and the qualitative moats that define your business. By identifying and addressing valuation "hair" early, you'll ensure that your firm is positioned as a premium asset rather than a commodity. It's the quality of your advisory team that remains the most significant variable in the final outcome.

Since 1987, Versailles Group has specialized in providing fairness opinions and boutique advisory services with a global reach. We prioritize senior-level expertise on every transaction, ensuring that your board's fiduciary duties are protected by seasoned professionals. Our methodical approach transforms uncertainty into a clear, actionable strategy for maximizing enterprise value. Contact Versailles Group for a Senior-Level Valuation Consultation to discuss your specific objectives. We look forward to helping you achieve an outcome that reflects the true worth of your firm's potential.

Frequently Asked Questions

What is the typical EBITDA multiple for a middle market company in 2026?

The average middle market company valuation multiple reached 7.1x EBITDA in the first half of 2026. For lower middle-market firms with over $10 million in EBITDA, multiples often climbed above 8.0x. These averages vary by sector, with premium deals commanding up to 9.8x. You shouldn't rely on broad medians alone. Your specific growth profile and operational maturity will ultimately dictate where your firm lands within this current market range.

How does a fairness opinion differ from a standard business valuation?

A fairness opinion is a specialized report delivered to a board of directors to validate that transaction terms are financially equitable. While a standard valuation provides an internal benchmark for pricing, a fairness opinion acts as a critical fiduciary shield. It helps protect directors from shareholder litigation during divestitures. This independent assessment is a cornerstone of our advisory work at Versailles Group, ensuring senior-level scrutiny of every deal component.

Can I use my tax returns to determine the value of my company?

Tax returns are generally unsuitable for determining enterprise value because their primary purpose is to minimize taxable income. A professional middle market company valuation uses normalized financial statements to highlight the true earning capacity of the asset. We adjust for non-recurring expenses and owner-specific costs to present a clear picture of future cash flows. Using tax filings as a benchmark often results in a significant undervaluation of the business.

What are the most common 'add-backs' used to normalize EBITDA?

Common add-backs include non-recurring expenses like one-time legal fees, excess owner compensation, and non-operating costs such as personal travel or club memberships. We also adjust for market rent if the company owns its real estate. These adjustments are vital for showing a buyer what the business would earn under new ownership. Identifying these expenses early ensures that the headline price remains defensible throughout the rigorous due diligence phase.

How much does customer concentration affect my company's valuation?

High customer concentration can trigger a valuation discount of 20% to 30% depending on the stability of the relationship. Buyers view a business that relies on a single client for more than 15% of its revenue as a higher-risk investment. If you have significant concentration, buyers will often propose aggressive earnouts to shift the risk back to you. Diversifying your client base before a sale is a highly effective way to preserve your multiple.

Why is a boutique investment bank better for valuation than a large bank?

Large investment banks often assign middle-market transactions to junior associates, which can lead to missed nuances during complex negotiations. A boutique firm like Versailles Group ensures that senior-level experts handle every stage of the process personally. This high-touch approach is essential for identifying unique value drivers and maintaining discretion. You receive the agility of a specialized partner combined with the institutional-grade expertise required for sophisticated national or cross-border transactions.

What happens if the buyer's valuation is lower than my advisor's estimate?

When a buyer's offer falls below your advisor's estimate, it often stems from differing assumptions regarding future growth or risk. We bridge this gap by presenting data-driven arguments for synergies or by restructuring the deal with earnouts. A lower offer isn't necessarily the end of the conversation; it's an opportunity to defend the price using the strategic frameworks established during the preparation phase. Professional advisory ensures you have the math to support your position.

How long does a formal middle market valuation process take?

A formal valuation as part of an M&A process typically takes four to six weeks to complete initially. However, the entire journey from preparation to closing a middle-market deal often spans six to nine months. This timeline allows for thorough financial normalization, buyer identification, and the rigorous due diligence required for sophisticated transactions. Rushing this process often leads to poor positioning and a lower final price, so a methodical pace is always preferred.

Sep 05

Family Business Exit Strategy: A Senior-Level Guide to Maximizing Value and Legacy

Arti Jain September 5, 2026

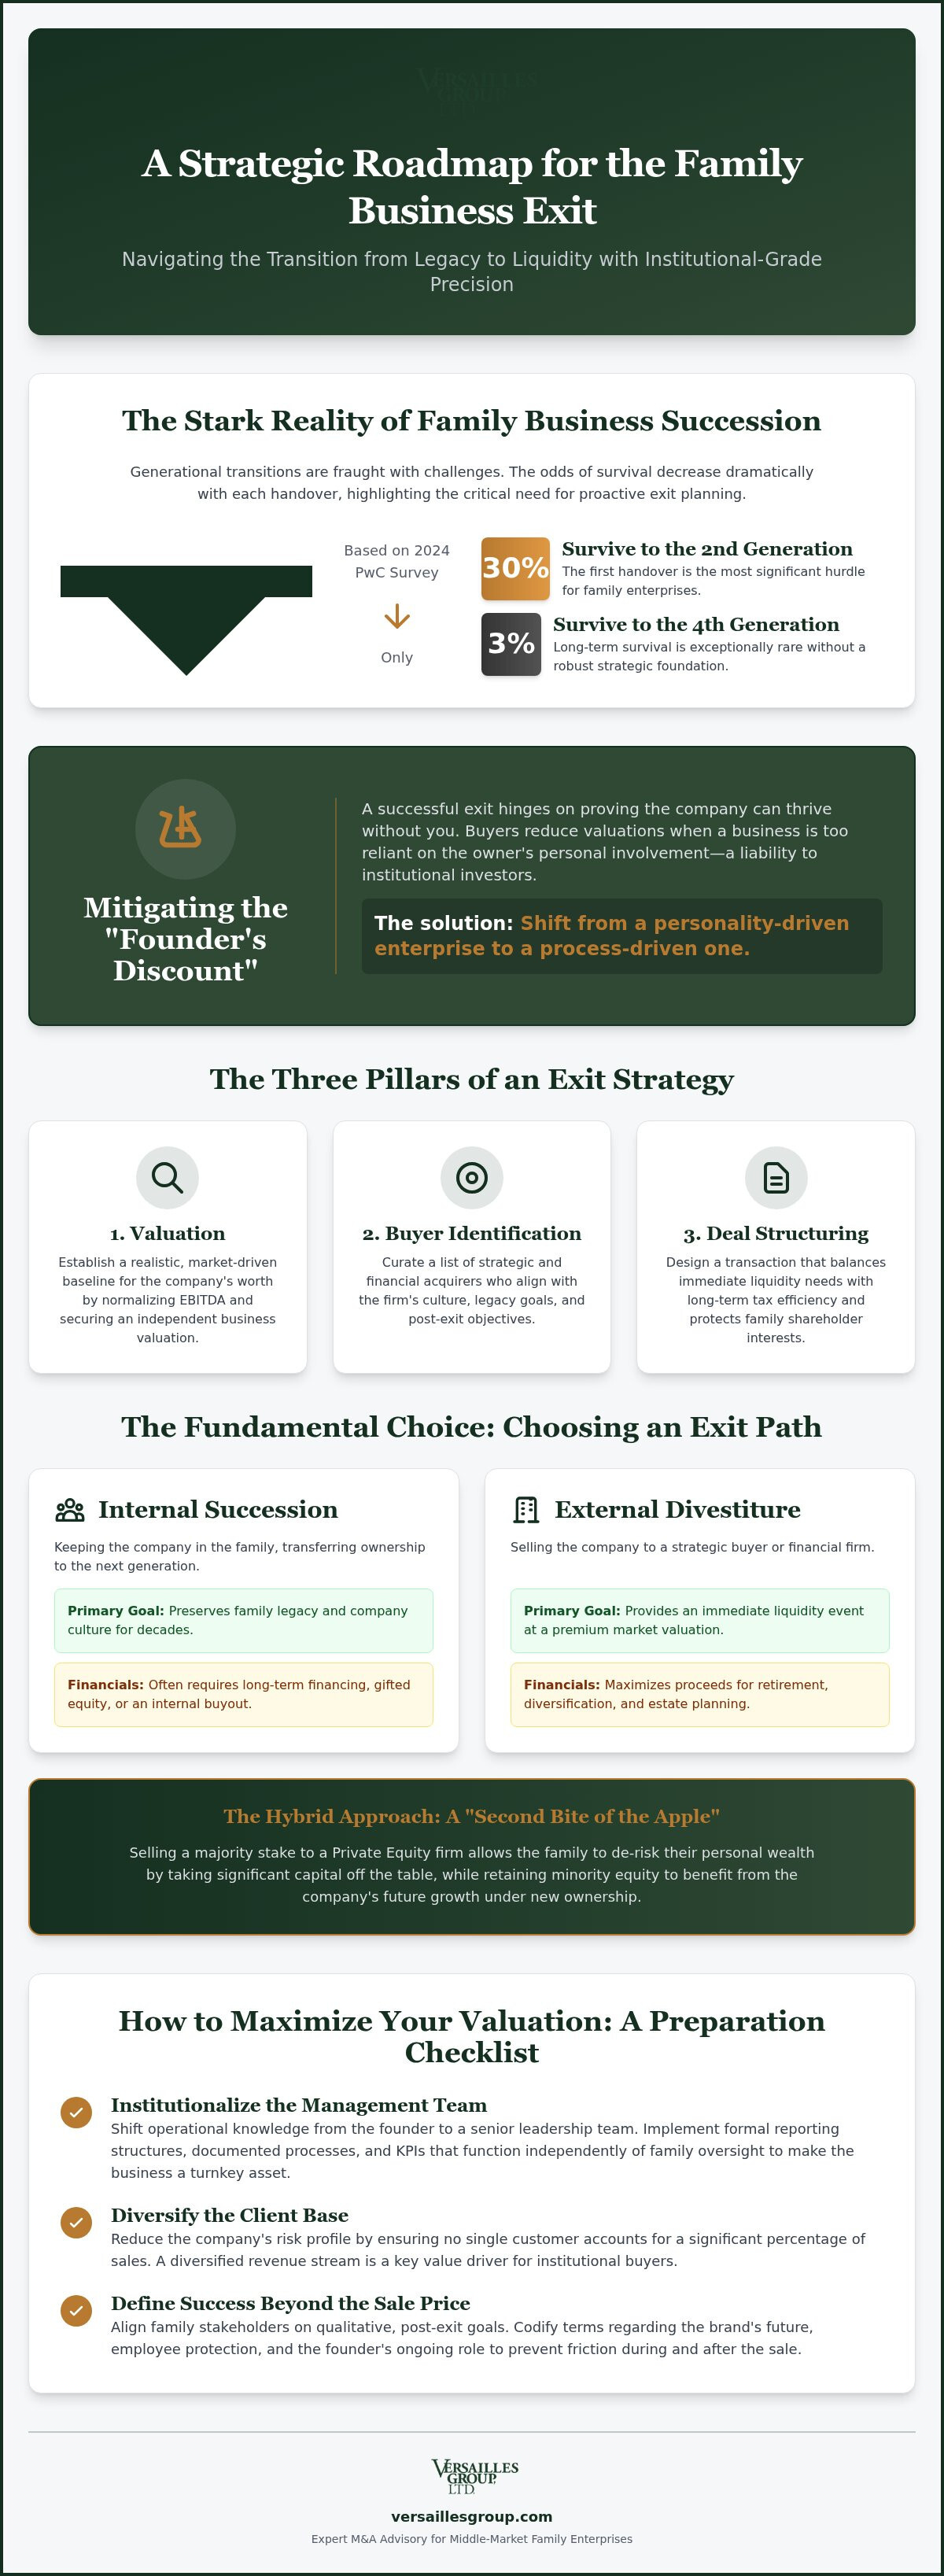
According to the 2024 PwC Family Business Survey, only 30% of family enterprises successfully transition to the second generation, while a mere 3% survive to the fourth. These figures represent more than just failed handovers; they reflect the immense difficulty of balancing emotional legacy with cold financial reality. You've spent decades building a name and a culture, so it's natural to feel anxious about the "founder's discount" or the potential for family conflict during a sale. Developing a comprehensive family business exit strategy is the only way to ensure your life's work isn't undervalued or dismantled by poor planning.

You deserve a transition that reflects the elite standards you've maintained. This guide outlines how to apply institutional-grade M&A tactics to your middle-market enterprise to secure maximum proceeds and a buyer who respects your history. We'll examine the critical choice between strategic buyers and financial firms, the impact of the $15 million individual tax credit in 2026, and the necessity of fairness opinions for family shareholders. By the end of this article, you'll have the clarity needed to execute a clean exit that protects your family's future and your company's enduring legacy.

Key Takeaways

  • Distinguish between internal generational succession and external divestitures to establish a clear roadmap for your company’s future.
  • Protect your valuation from the "Founder's Discount" by institutionalizing management and diversifying your revenue streams before seeking a buyer.
  • Compare the motivations of strategic acquirers and financial firms to identify the partner that best aligns with your post-exit objectives.
  • Manage the complexities of a family business exit strategy with a senior-level execution roadmap that prioritizes discretion and precision.
  • Leverage the boutique advantage of dedicated senior-level advisory to address the complex emotional and financial nuances of a middle-market divestiture.

The Strategic Framework for a Family Business Exit

A family business exit strategy isn't a single event; it's a structured roadmap designed to transfer both ownership and leadership while preserving the enterprise's underlying value. Many founders treat an exit as a reaction to market conditions or health concerns. This reactive posture often leads to diminished valuations and rushed decisions. Proactive planning, conversely, allows you to dictate the terms of your departure. It requires a focus on three core pillars:

  • Valuation: Establishing a realistic, market-driven baseline for the company's worth.
  • Buyer Identification: Curating a list of strategic and financial acquirers who align with the firm's culture.
  • Deal Structuring: Designing a transaction that balances immediate liquidity with long-term tax efficiency.

Waiting for the "perfect" market cycle is rarely a winning strategy. By the time the market peaks, you've likely missed the window to optimize your operations for a sale. A well-constructed strategy ensures you're prepared to move when the right buyer emerges, rather than being forced to accept terms under duress.

Internal Succession vs. External Divestiture

Choosing between keeping the company in the family or pursuing an external sale is the most fundamental decision in succession planning. If the next generation possesses both the aptitude and the interest to lead, an internal transfer can preserve the family's legacy for decades. However, the financial implications vary significantly. An internal transfer often requires long-term financing or gifted equity, whereas an external divestiture provides an immediate liquidity event at a market premium. For families who aren't ready for a full exit, a hybrid approach exists. Selling a majority stake to a private equity firm allows the family to de-risk their personal wealth while retaining a "second bite of the apple" through minority equity.

Defining Success Beyond the Sale Price

While the headline number is vital, a truly successful exit addresses qualitative objectives that the sale price alone cannot satisfy. You must align family stakeholders on what happens after the closing. Does the brand name remain? Are long-term employees protected through specific contract clauses? These legacy goals define the true value of a deal. Additionally, your post-exit role must be codified early. Some founders prefer a clean break, while others find value as a consultant or chairman of the board. Establishing these boundaries prevents the friction that often arises when a buyer's vision clashes with a founder's lingering influence. Don't leave these details to chance during the final hours of negotiation.

Valuation and Preparation: Mitigating the Founder's Discount

A successful family business exit strategy hinges on your ability to prove the company can thrive without you. This reality often leads to the "Founder's Discount," a significant reduction in valuation applied by buyers when they perceive the business is too reliant on the owner's personal involvement. To an institutional investor, a business that requires the founder's daily oversight is a liability. Maximizing your multiple requires shifting from a personality-driven enterprise to a process-driven one.

Institutional buyers focus on three key value drivers: recurring revenue, a diversified client base, and robust management. If a significant percentage of your sales comes from a single customer, your risk profile increases. Preparation also involves normalizing EBITDA. This process of "cleaning the books" involves removing non-recurring expenses and personal items to reveal the firm's true earning potential. An independent business valuation provides the necessary benchmark to set realistic expectations before you ever enter the market.

Professionalizing the Management Team

Institutional buyers don't just buy your past; they buy your future stability. You must shift operational knowledge from your own mind to a senior leadership team. This involves implementing formal reporting structures and KPIs that function independently of family oversight. When proprietary processes are documented and managed by a capable team, the business becomes a turnkey asset. It's no longer a personal job; it's a scalable machine. This transition is often the most difficult part of a family business exit strategy, yet it's the one that yields the highest return on investment.

Strategic Positioning for Higher Multiples

Higher multiples are often found in "hidden" assets. Intellectual property, proprietary software, or a dominant share of a niche market can command a premium from the right acquirer. Crafting a narrative that highlights these growth opportunities is essential for attracting elite interest. Engaging in sell-side M&A advisory with senior-level experts ensures these nuances aren't lost in a generic pitch deck. These advisors identify value-add buyers who see the strategic potential that a standard balance sheet alone cannot convey. By identifying these assets early, you position the firm as a platform for growth rather than a stagnant legacy business.

Strategic vs. Financial Buyers: Choosing the Right Successor

A critical junction in any family business exit strategy is determining who'll lead the enterprise into its next chapter. The choice isn't merely about the highest bidder; it's about the fundamental future of the company's identity. Generally, buyers fall into two distinct categories: strategic acquirers and financial sponsors. Understanding the motivations of each is essential for aligning your financial goals with your personal legacy. The path you choose will dictate everything from the final sale price to the level of autonomy your management team retains.

The Synergy Premium of Strategic Acquirers

Strategic buyers are typically competitors or companies within a related industry. They're motivated by synergies, which is the ability to combine operations to reduce costs or expand market reach. Because they can justify a higher price based on these anticipated gains, they often provide the highest upfront valuation. However, this premium often comes at a cost to the company's existing culture. Integration usually involves merging departments or rebranding, which can dilute the family brand identity you've spent decades building. When negotiating with these entities, confidentiality is paramount. You're effectively showing your playbook to a competitor, making senior-level discretion a non-negotiable requirement for protecting your market position.

Private Equity and the 'Second Bite of the Apple'

Financial buyers, such as Private Equity (PE) firms or family offices, view your business as an investment vehicle rather than an operational extension. They often prefer a recapitalization model where the family retains a significant minority stake. This "second bite of the apple" allows you to de-risk your personal wealth today while participating in the upside when the PE firm eventually sells the business, often within a five to seven year window. This path provides institutional capital to scale the business further and usually keeps the existing management team in place. It's an ideal solution for founders who aren't ready for a full departure but want to secure their family's financial future through a professional partnership.

The decision ultimately rests on your tolerance for change. A strategic sale often results in a clean break and maximum immediate liquidity, but it risks the total absorption of your legacy. A financial sale offers operational continuity and the potential for greater long-term gains; however, it requires you to answer to a board of institutional investors. Balancing these factors is a nuanced exercise that requires more than just a spreadsheet. It requires a deep understanding of the buyer's long-term intent and their track record with family-owned firms.

Family business exit strategy

The M&A Process: A Senior-Level Execution Roadmap

Executing a family business exit strategy requires a methodical transition from high-level planning to rigorous market engagement. A standard middle-market divestiture typically spans six to twelve months, moving through phases of preparation, marketing, and closing. The process begins with the creation of a Confidential Information Memorandum (CIM). This isn't a simple marketing brochure; it's an institutional-grade document that details your financials, operations, and growth prospects to attract elite buyers who value precision and transparency.

Once the CIM is in the market, the filtering process begins. You'll first receive Indications of Interest (IOIs). These serve as non-binding benchmarks to gauge a buyer's valuation range and intent. From there, you'll narrow the field to a select few who'll submit a formal Letter of Intent (LOI). The LOI is a pivotal document that grants a buyer exclusivity. It's the primary tool for filtering out candidates who lack the capital or cultural alignment to complete the transaction.

Maintaining Confidentiality Throughout the Sale

The risk of "leakage"—where employees, customers, or competitors learn of a pending sale—can destabilize a company during its most vulnerable period. To mitigate this, senior advisors use a "blind" profile. This one-page summary describes the business's attributes without revealing its identity. It allows us to qualify buyers before any sensitive data is exchanged. A boutique advisor manages these communication flows personally. This ensures your market position remains secure until the deal is finalized.

Navigating the Due Diligence Minefield

The due diligence phase is often the most taxing part of the journey. Buyers will scrutinize every legal contract, financial statement, and operational process. We streamline this by preparing a Virtual Data Room (VDR) well in advance. This centralized hub ensures that the review process is efficient. Proactive preparation allows you to identify and address potential "deal killers," such as unresolved litigation or tax discrepancies, before they derail the closing. Managing the emotional fatigue of these final negotiations is where senior-level involvement proves its value. A steady hand keeps the focus on the objective while you continue to run the business.

If you're preparing for a transition, our sell-side M&A advisory provides the senior-level expertise necessary to manage these complex mechanics with discretion and precision.

The Boutique Advantage in Family Business Divestitures

Large investment banks often operate on a volume-based model that prioritizes the largest transactions. For a middle-market family enterprise, this often means your deal is handed off to junior associates who lack the lived experience to handle complex family dynamics. A boutique approach offers a stark contrast. Since 1987, Versailles Group has provided senior-level attention on every deal, ensuring that the nuances of your business aren't lost in a standardized process. This high-touch partnership is vital when executing a family business exit strategy, where discretion and specialized expertise are the primary drivers of success. Junior staff may lack the sensitivity required to manage the intersection of private wealth and corporate governance, making senior-level involvement a necessity rather than a luxury.

One critical component of an institutional-grade exit is the Fairness Opinion. This independent valuation protects the board and shareholders from liability by validating that the deal terms are financially fair. In a family setting, where multiple generations or passive shareholders may be involved, this document provides the objective evidence needed to prevent future disputes. It's a layer of security that larger firms might overlook for middle-market deals, but one we consider essential for a clean transition. By securing a Fairness Opinion, you provide a shield against potential litigation and ensure that all stakeholders feel the outcome is equitable.

Elite Strategy for the Middle Market

Tailoring an M&A process for enterprises valued between $20 million and $250 million requires a specific set of tools. You don't want your company treated as a commodity in a broad auction that devalues your brand. Instead, we position your business as a "must-have" asset for specific buyers who understand your niche. Our global perspective allows us to look beyond domestic borders to identify international strategic acquirers who may offer a higher premium to enter a new market. This level of precision ensures you aren't just selling a company; you're maximizing a life's work through a bespoke family business exit strategy.

The Role of the Trusted Advisor

Family business transitions are rarely just about the numbers. They involve deep-seated emotions, long-term employee relationships, and complex family politics. A boutique advisor acts as a necessary buffer between these internal dynamics and the hard-nosed negotiations of the M&A market. We provide results-oriented guidance that remains objective, even when family tensions run high. By acting as a steady hand, we ensure the transaction stays on track while you focus on your family's future. This objective stance allows us to negotiate from a position of strength, unencumbered by the emotional weight of the business's history.

Discover how Versailles Group’s senior-level advisory maximizes your family business exit.

Securing Your Legacy Through Strategic Execution

Transitioning away from a business you've built requires more than a simple valuation; it demands a shift from operational management to strategic stewardship. We've explored how professionalizing your leadership team mitigates the founder's discount and why choosing between a strategic or financial buyer dictates your long-term autonomy. A successful family business exit strategy isn't found in a template. It's forged through meticulous preparation and the use of institutional-grade documents to command elite interest.

Since 1987, we've specialized in providing the senior-level attention that middle-market enterprises deserve. You don't have to navigate these complex family dynamics or hard-nosed financial negotiations alone. Our boutique approach ensures your legacy is protected while your financial outcomes are maximized. By prioritizing discretion and precision, you can exit with the confidence that your company's future is secure.

Schedule a confidential consultation with our senior M&A advisors. Your life's work deserves an elite transition.

Frequently Asked Questions

What is the most common mistake in a family business exit strategy?

The most common mistake is a lack of proactive preparation, often resulting in a reactive sale under duress. Many owners wait until a health crisis or market downturn to begin their family business exit strategy, which severely limits their leverage. By failing to institutionalize processes or professionalize management early, founders often face a "founder's discount" that significantly reduces the final sale price. Starting the planning process three to five years before a desired exit is the most effective way to maximize value.

How long does it typically take to sell a middle-market family business?

Selling a middle-market family business typically takes between six and twelve months from the initial preparation phase to the final closing. This timeline accounts for the creation of a Confidential Information Memorandum, identifying and qualifying buyers, and the rigorous due diligence process. External factors, such as interest rate fluctuations or industry-specific regulatory changes, can extend this duration. Maintaining operational focus during this period is essential to ensure the company's performance doesn't dip while negotiations are underway.

Should I tell my employees I am planning to sell the business?

You should generally wait until a Letter of Intent is signed and due diligence is nearing completion before informing the broader employee base. Early disclosure can lead to "leakage" that creates uncertainty, potentially causing key talent to seek other opportunities. While transparency is a core family value, protecting the transaction's confidentiality is vital for business stability. In some cases, a small group of senior executives may be informed earlier if their cooperation is necessary for the due diligence process.

What is the difference between a succession plan and an exit strategy?

A succession plan focuses on the transfer of leadership and management responsibilities, whereas an exit strategy focuses on the transfer of ownership and the realization of financial value. Succession planning ensures the company's operational continuity, often within the family or current management. An exit strategy addresses the broader liquidity event, whether through an internal transfer, a strategic sale, or a private equity recapitalization. Both are essential, but they serve different long-term objectives for the founder.

How do I determine the fair market value of a family-owned company?

Determining fair market value requires a professional valuation that analyzes normalized EBITDA, industry-specific multiples, and comparable transaction data. Unlike public companies, middle-market family firms often have personal expenses or non-recurring items that must be "cleaned" from the books to reveal true earning potential. A senior-level advisor uses these adjusted figures to establish a realistic price range. This process ensures that you enter the market with expectations grounded in current institutional-grade financial standards rather than guesswork.

Can I sell my business to a competitor without them stealing my trade secrets?

Yes, you can safely engage with competitors by using a "blind" profile and staging the disclosure of sensitive information. A boutique advisor acts as a buffer, qualifying potential buyers before revealing the company's identity or proprietary data. Non-disclosure agreements provide legal protection, but the strategic timing of information release is your best defense. Trade secrets and customer lists are typically only shared in the final stages of due diligence after a firm commitment is made.

What is a Fairness Opinion and why does my family board need one?

A Fairness Opinion is an independent report that validates whether the financial terms of a proposed transaction are fair to the company's shareholders. Family boards need this document to mitigate the risk of litigation and to ensure that all family members, including passive shareholders, feel the deal is equitable. It provides an objective benchmark that transcends family politics. In complex divestitures, this formal opinion serves as a critical shield for directors, proving they've fulfilled their fiduciary duties with professional diligence.

What happens to the company name and legacy after a strategic sale?

The fate of your company's name and legacy depends heavily on the type of buyer you select. Strategic buyers often merge operations and may eventually rebrand the entity to align with their global identity. Conversely, financial buyers like private equity firms often keep the existing brand and management in place to serve as a platform for future growth. Defining your legacy goals early in the family business exit strategy allows you to prioritize buyers who'll respect the history you've built.

Sep 04

When to Sell a Business: A Strategic Framework for Middle-Market Owners

Versailles Group September 4, 2026

Is the most significant risk to your legacy the decision to exit, or the choice to wait one year too many? For middle-market owners, the question of when to sell a business is rarely about a single financial metric. It's a complex weight involving the welfare of your employees, the fear of missing a market peak, and the quiet anxiety of what your identity becomes after the closing date. You've spent decades building an institution of value; it's only logical to feel protective of its future and your own.

This article provides a strategic framework to master the convergence of market cycles, operational performance, and personal readiness. With middle-market valuations averaging 7.0x EBITDA in the second quarter of 2026, the current environment offers a stabilized window for those prepared to act. We'll examine how to identify your optimal exit window to achieve maximum valuation while minimizing deal risk. You'll gain a methodical perspective on aligning your company's maturity with sophisticated buyer demands, ensuring a transition that honors your legacy and secures your financial future with absolute confidence.

Key Takeaways

  • Identify the "Optimal Exit Window" as the precise intersection where peak internal company performance meets high external market demand.
  • Recognize how macroeconomic signals and industry consolidation phases dictate the most advantageous time when to sell a business.
  • Leverage the growth S-curve to exit while momentum is still accelerating; this maximizes valuation and minimizes perceived deal risk for buyers.
  • Audit your personal readiness and succession planning to ensure a transition that protects your identity and honors the company's legacy.
  • Utilize senior-level, boutique advisory to navigate the complexities of middle-market transactions with a degree of precision and discretion that larger institutions often lack.

Understanding the Optimal Exit Window: When to Sell a Business

Success in the middle market isn't merely the result of operational excellence; it's the product of precise timing. Many owners view the decision of when to sell a business as a response to fatigue or an unsolicited offer. However, treating timing as a strategic lever allows a founder to dictate terms rather than merely accepting them. This transition from a reactive posture to a proactive strategy differentiates a standard exit from a legacy-defining transaction.

The Optimal Exit Window is the specific point where internal growth momentum intersects with peak external market liquidity.

Delaying an exit often introduces the risk of "The Plateau." This is the stage where a company’s growth rate begins to level off, even if total revenue remains high. Buyers pay for future potential, not just past performance. When a business enters a plateau, the perceived risk increases and the valuation multiple typically contracts. A tactical sale is often reactive, triggered by a sudden crisis or an unexpected approach. In contrast, a strategic divestiture is a deliberate move planned years in advance to capitalize on favorable conditions while the growth trajectory is still steep.

The Cost of Misaligned Timing

Selling during a market down cycle can severely erode the value built over decades. For instance, while middle-market valuations averaged 7.0x EBITDA in the second quarter of 2026, a shift in interest rates or economic sentiment can quickly compress these multiples. When multiples contract, the same level of performance yields a significantly lower enterprise value. Beyond the financial impact, there's a significant psychological toll. "Seller Remorse" frequently stems from being forced into a sale by circumstances rather than choosing the moment of exit. An unprepared owner often faces higher deal risk and a more difficult post-sale identity transition.

The Fiduciary Duty of Timing for Boards

For companies with formal governance, the board of directors holds a clear fiduciary responsibility to evaluate exit opportunities. This duty requires balancing the immediate interests of shareholders with the long-term viability of the enterprise. In the context of Mergers and acquisitions (M&A), boards must objectively assess whether the current market offers a premium that outweighs the projected value of continued independent operations. Fairness opinions serve as a critical tool in this process, providing an independent valuation that validates the timing and terms of the transaction. By institutionalizing the review of exit options, boards ensure that the decision of when to sell a business remains rooted in data and strategic logic rather than emotion.

Macroeconomic and Industry Signals: External Triggers for an Exit

The decision of when to sell a business is often dictated by forces beyond the boardroom. While internal performance provides the foundation, external macroeconomic signals act as the catalyst for a premium valuation. Understanding these triggers requires a perspective that looks past immediate revenue to the broader flow of global capital and regulatory shifts.

Capital Market Liquidity and Interest Rates

Debt availability serves as the engine for middle-market transactions. When credit is accessible and affordable, strategic buyers can leverage their balance sheets to offer more aggressive purchase prices. Conversely, high interest rates create a direct downward pressure on EBITDA multiples. As of August 2026, SBA 7(a) variable-rate ceilings sit between 9.75% and 13.25%. These elevated financing costs mean buyers must be more selective, often requiring higher returns to justify the debt service. An overheated market is typically marked by loose lending standards and rapid-fire deal closures, whereas a cooling market sees a flight to quality. Identifying these shifts early allows an owner to exit before a liquidity crunch limits the pool of viable bidders.

Industry-Specific Consolidation Cycles

Every sector eventually moves through a phase of intense consolidation, often referred to as "The Great Roll-up." During these windows, larger entities and private equity platforms aggressively acquire smaller competitors to gain market share or geographic reach. You must determine if your firm is positioned to be the hunter or the prey. Being the last independent player in a fully consolidated market is a precarious position; you may find yourself with fewer exit options and diminished leverage. The entry of global competitors into your niche is another clear signal. When international firms begin looking for domestic beachheads, they often pay a premium for established middle-market leaders.

Private equity firms currently face a near-record nine-year backlog to clear existing portfolio inventories. This creates a unique pressure for these firms to deploy "dry powder" and realize returns for their limited partners. Additionally, the "One Big Beautiful Bill Act" of 2025 has made the 20% QBI deduction and 100% bonus depreciation permanent. This legislative certainty removes a significant layer of tax risk, making the current environment particularly attractive for a strategic divestiture. When regulatory stability aligns with high buyer urgency in Mergers and acquisitions (M&A), the window for a maximum-value exit opens wide.

Internal Business Performance: Identifying the Value Peak

While macroeconomic signals provide the context for a transaction, your company's internal health determines the final multiple. Identifying the value peak requires an objective look at the "Growth S-Curve." The most advantageous time when to sell a business is often before it reaches its absolute summit. Buyers pay for momentum. If you sell at the plateau, you're selling history. If you sell during the acceleration phase, you're selling a future that the buyer is eager to fund.

Quality of EBITDA is paramount in the middle market. Buyers prioritize recurring revenue streams over one-off projects because they suggest stability and lower post-acquisition risk. Beyond the numbers, sophisticated investors scrutinize your operational dependencies. Middle-market firms often suffer from customer or supplier concentration. If a single client accounts for more than 15% of your revenue, buyers see a significant risk to the company's longevity. Diluting this concentration before starting an exit process is essential for protecting your valuation.

The "Leave Some Meat on the Bone" Strategy

It's a common mistake to wait until every growth opportunity is exhausted. Sophisticated buyers, particularly private equity firms with "dry powder" to deploy, look for an untapped growth roadmap. By leaving some expansion potential on the table, you provide the buyer with a clear path to their own return on investment. This creates a more competitive bidding environment. Selling at the absolute peak often leads to a "perfect performance" trap where any slight dip during due diligence can derail the deal or lead to aggressive retracing.

Infrastructure and Operational Scalability

Operational readiness is often the bottleneck in middle-market exits. Buyers scrutinize whether your existing systems can handle institutional-scale growth without collapsing. Clean, audited financial records aren't just a preference; they're the baseline for trust in a high-stakes transaction. A transition is much more likely to succeed when the underlying infrastructure is robust enough to support a larger organization. When your senior management team can operate independently of your daily oversight, you've reached a state of maximum sell-readiness. A deep management bench increases the probability of a successful divestiture because it assures the buyer that the company's institutional knowledge won't walk out the door with the founder.

Personal and Psychological Readiness: The Founder’s Audit

The decision of when to sell a business is often the most significant personal choice an owner will ever make. While financial metrics provide the logic, personal readiness provides the permission. Founder burnout is a tangible business risk; when an owner’s energy wanes, the company's growth trajectory often follows. This decline can happen subtly, yet it significantly impacts valuation during due diligence. If you find yourself more focused on protecting what you've built than on aggressively pursuing new markets, you've likely reached a critical inflection point. Wealth diversification is another primary driver. If a significant percentage of your net worth is tied to a single asset, you're exposed to sector-specific risks that could jeopardize your long-term security.

Succession and Legacy Considerations

A well-structured exit requires more than just a high valuation; it requires a clear vision for the company's life after the transaction concludes. Many owners struggle with the choice between a clean break and an equity rollover. A clean break offers immediate liquidity and a total exit. Conversely, an equity rollover allows the owner to participate in the "second bite of the apple" alongside a private equity partner. Choosing the right buyer is the only way to ensure the company's culture survives the transition. A strategic buyer might integrate operations to achieve synergies, while a financial buyer might keep the existing brand and management team intact. Senior-level advisory is essential here to navigate these nuances with discretion. Owners seeking to evaluate their personal and financial readiness can benefit from the sell-side M&A advisory expertise of a seasoned partner who understands the emotional weight of a legacy transition.

Financial Planning and Post-Sale Objectives

The "headline price" is rarely the amount that hits your bank account. You must account for taxes, escrow holdbacks, and transaction fees to determine your true walk-away cash. Calculating "The Number" involves assessing whether the net proceeds after taxes will support your desired lifestyle and philanthropic goals. Without this clarity, owners often experience "Seller Remorse" even after a successful closing. You must also consider your identity beyond the office. What will you do on day 101? A successful transition involves planning for your next chapter with the same rigor you applied to building your firm. Psychological readiness is the state where the desire for the next chapter outweighs the attachment to the current one. When your financial objectives align with this mental shift, the window for an optimal exit is fully open.

Executing a Strategic Exit with Versailles Group

Deciding when to sell a business is a high-stakes calculation that demands more than just a favorable market. It requires an execution strategy that preserves the value you've spent years, or perhaps decades, building. In the middle market, the quality of your advisory team often dictates the final enterprise value. While large institutional banks frequently delegate middle-market transactions to junior associates, Versailles Group has maintained a commitment to senior-level involvement in every deal since 1987. This boutique attentiveness ensures that your transaction receives the weight of experience it deserves, providing a steady hand through the complexities of due diligence and closing.

The Senior-Level Boutique Advantage

Middle-market owners require a level of sensitivity and discretion that larger, volume-driven institutions often fail to provide. Our approach to sell-side M&A advisory is rooted in bespoke strategy rather than one-size-fits-all templates. We understand that your company’s value isn't just found in the EBITDA, but in the proprietary processes, management depth, and market position you've established. By leveraging a global perspective, we identify and engage elite buyers who might be overlooked by firms with a purely domestic focus. This international reach, combined with our success-based transaction fee model, ensures our interests are perfectly aligned with yours. We don't just facilitate a sale; we orchestrate a strategic divestiture that maximizes your walk-away cash and honors your legacy.

Initiating the Sell-Side Advisory Process

The path to a successful exit begins long before the first bidder signs a non-disclosure agreement. A confidential and methodical process is essential to protect your company's operational stability and employee morale. Our process starts with a rigorous preliminary valuation and strategic assessment. This phase helps confirm if your internal performance truly aligns with the current market cycle. Once the optimal window is confirmed, we prepare a Confidential Information Memorandum (CIM). This document is more than a financial summary; it's a sophisticated narrative designed to attract buyers who see the long-term potential of your firm. This structured approach creates competitive tension among bidders, which is the most effective way to minimize deal risk and secure a premium multiple.

A transition of this magnitude shouldn't be handled by a firm that treats your legacy as just another entry in a deal log. It requires a partner who prioritizes quality over volume and brings decades of institutional-grade expertise to the table. If you're evaluating your readiness for a transition, we invite you to take the first step toward a secure and prestigious exit. Contact Versailles Group for a confidential strategic assessment to begin the journey of identifying your company's true market potential.

Securing Your Legacy Through Strategic Timing

Identifying the precise moment when to sell a business requires a rare alignment of internal operational excellence and favorable macroeconomic conditions. You've cultivated a company with a robust management team and clean financial records; now you must navigate the external landscape of capital liquidity and industry consolidation. A successful exit is not merely about reaching the peak of the growth S-curve. It is about ensuring your personal readiness matches the market's appetite for your legacy.

Versailles Group has served as a steady hand for middle-market owners since 1987. As a boutique investment bank, we prioritize quality over volume, ensuring senior-level involvement in every transaction. Whether you are navigating a domestic divestiture or a complex cross-border M&A deal, our bespoke approach provides the discretion and precision your life's work deserves. The right timing is a strategic choice that protects your net worth and secures the future of your organization. Maximize your exit value with senior-level M&A advisory from Versailles Group. Your next chapter begins with a methodical, expert-led transition that honors everything you've built.


Frequently Asked Questions

How long does the typical business sale process take in the middle market?

A typical middle-market transaction takes six to twelve months from initial engagement to closing. This timeline includes several distinct phases: strategic preparation, buyer identification, and intensive due diligence. Rushing this process often leads to valuation erosion or missed risks. A methodical approach ensures the business is presented at its peak value, allowing sufficient time for sophisticated buyers to complete their internal approvals and financing arrangements.

Should I sell my business now or wait for lower interest rates?

Deciding when to sell a business involves balancing financing costs against operational momentum. While lower interest rates generally support higher valuation multiples, waiting for a specific rate environment introduces significant market risk. If your company is currently experiencing strong growth or industry consolidation is peaking, the benefits of acting now may outweigh the potential gains from a slight decrease in future borrowing costs. Strategic buyers often prioritize market share over interest rate fluctuations.

What is the most common reason middle-market business sales fail?

Failed transactions often stem from deal fatigue or unexpected discoveries during the due diligence phase. When an owner is unprepared for the rigors of an institutional-grade audit, minor financial or operational discrepancies can derail the process. Maintaining momentum is critical; delays allow external market conditions to shift or buyers to lose interest. Working with senior-level advisors helps mitigate these risks by identifying potential deal-breakers before the business reaches the open market.

How do I determine the right EBITDA multiple for my industry?

Industry multiples are dynamic and depend on sector-specific growth rates and buyer demand. For example, in the second quarter of 2026, business services saw average valuations of 7.5x EBITDA, while manufacturing averaged 7.1x. Your specific multiple will also be influenced by the quality of your recurring revenue, management depth, and operational scalability. A formal valuation or fairness opinion provides the most accurate baseline for your company's current market position.

Can I sell my business if I still want to remain involved in the operations?

Many owners choose to remain involved post-sale through an equity rollover or a multi-year transition agreement. This structure is particularly common with financial buyers who value the founder's institutional knowledge and leadership. It allows you to realize significant liquidity today while participating in the company's future growth. We help structure these divestitures to ensure your continued involvement aligns with both your personal lifestyle goals and the buyer's operational requirements.

What is the difference between a strategic buyer and a financial buyer regarding timing?

Strategic buyers typically focus on long-term synergies and competitive positioning, making them less sensitive to short-term market cycles. They may pay a premium to acquire proprietary technology or market reach. Financial buyers, such as private equity firms, are often driven by investment cycles and the availability of debt financing. Understanding these motivations is essential when determining when to sell a business to achieve the highest possible valuation and the most favorable deal terms.

How much does it cost to hire an investment bank for a sell-side transaction?

Professional M&A advisory typically involves a combination of success-based transaction fees and strategic advisory retainers. The success fee is calculated as a percentage of the total transaction value, ensuring the firm's interests are perfectly aligned with yours. Retainers cover the intensive work of valuation, marketing material preparation, and buyer identification. This structure guarantees that you receive senior-level attention throughout the complex process of preparing for and executing a high-stakes divestiture.

Is it possible to sell a minority stake instead of the entire business?

Selling a minority stake through a private placement is a viable strategy for owners seeking partial liquidity or growth capital without relinquishing control. This approach allows you to de-risk your personal balance sheet while retaining the majority of the upside potential. It is an effective solution for family enterprises or firms needing institutional-grade capital to fund a major expansion. We provide the senior-level guidance necessary to identify the right minority partners for these specialized transactions.

Aug 12

The M&A Market Is Active. So Why Are Deals Still Failing?

Versailles Group August 12, 2026

The U.S. M&A market looks stronger in 2026. Announced deal value reached approximately $1.2 trillion during the first five months of the year, nearly twice the level recorded during the same period in 2025, according to PwC.[1] Strategic buyers remain active. Private capital is available. Financing markets are functioning.

The underlying market is less forgiving. U.S. transaction volume declined modestly even as aggregate deal value surged, with larger transactions accounting for much of the increase.[1] In the lower middle market, buyers continue to pursue attractive companies, but valuation disagreements are becoming a more visible source of friction.

The market is not broadly repricing businesses higher. It is increasingly distinguishing between those buyers are willing to compete for and those they will consider only at a discount.

A Recovery Defined by Selectivity

Describing the current M&A environment as simply strong or weak is unhelpful. PwC counted 4,653 announced U.S. transactions during the first five months of 2026, down approximately 4% from the comparable prior-year period, even as total announced value nearly doubled.[1] BCG has observed a similar pattern globally: deal value rose sharply while transaction activity remained uneven.[2]

The lower middle market reflects the same divide. In a July survey of 79 buyers and M&A advisors, Axial found that 87% expected transaction activity to remain steady or increase during the second half of 2026. Ninety-one percent expected buyer competition to remain steady or increase.[3]

Those findings suggest a market with available capital and continued buyer interest, but not one in which every asset benefits equally. Businesses with durable earnings, defensible margins, diversified customers and credible management teams can still draw substantial interest. Companies with weaker earnings quality, concentrated customers, owner dependence or aggressive forecasts may still transact, but often with greater resistance on price and terms.

The more useful distinction is not between a good market and a bad one. It is between businesses whose risk profiles invite competition and those whose risks must first be discounted, structured around or explained.

Valuation Has Moved to the Center of the Negotiation

The clearest indication comes from transactions that do not close. In Axial's midyear survey, 57% of respondents identified valuation expectations as the leading reason transactions failed during the first half of 2026. That compares with 28% for transactions that failed in 2025. Timing and process fatigue accounted for another 16%. Only 10% cited diligence findings, 9% macroeconomic uncertainty and 8% financing constraints.[3] Valuation appears to be playing a larger role in stalled transactions than it did a year ago.

A buyer can be interested. Debt can be available. A business can generate multiple indications of interest. None of that settles the question of value. Sellers and buyers also approach that question from different directions.

Owners naturally give weight to what has already been built: growth, customer relationships, intellectual property, market position and years of investment. Transaction comparables can reinforce those expectations, especially when the most visible precedents involve exceptional assets.

Buyers underwrite what happens next. They are paying today for cash flows that remain uncertain. Customer retention, margin durability, management depth, capital requirements, financing costs and execution risk all affect what those future earnings are worth.

The seller is often pricing what the company has become. The buyer is pricing both what it could become and what could go wrong. The resulting gap is not always evidence of unreasonable expectations. Instead, it reflects a disagreement over the quality and risk of future earnings.

Earnings Quality Is Widening the Valuation Spread

Market multiples can create a false sense of precision. A company producing $5 million of EBITDA with recurring revenue, diversified customers, stable margins and independent management is not economically equivalent to one producing the same EBITDA while relying on a founder, a small number of customers or unusually favorable recent conditions.

The earnings may be identical. Their durability is not. Buyers are not purchasing EBITDA in isolation. They are underwriting the probability that those earnings survive the change in ownership and continue to grow.

Axial's respondents identified competition for quality assets as the leading source of upward valuation pressure in the second half of 2026. Business performance and financing conditions were among the principal sources of downward pressure.[3] That suggests the spread between stronger and weaker assets may matter more than movements in the average market multiple.

Buyers continue to pay attractive prices where conviction is high. They appear less willing to extend the same treatment to businesses carrying greater execution or earnings risk.

Transaction Structure Is Part of Valuation

Nearly two-thirds of Axial's respondents expect valuation multiples to remain broadly stable during the second half of 2026. At the same time, dealmakers reported greater use of seller financing, earnouts, holdbacks, and other forms of contingent consideration.[3]

SRS Acquiom's 2026 lower-middle-market deal terms analysis found that 35% of transactions with closing payments of $25 million or less included an earnout. Among deals of $50 million or less, the figure was 29%.[4]

Structure can make two nominally identical offers economically very different. A $50 million offer paid entirely in cash at closing is not equivalent to a $50 million headline value that includes an earnout, rollover equity or deferred consideration. Escrows, working-capital adjustments, indemnification obligations and financing conditions can widen the difference further. The highest nominal offer is not necessarily the strongest transaction.

These mechanisms can bridge genuine valuation disagreements. They can also transfer risk. If the buyer believes the seller's forecast, it can pay for it. If the buyer remains uncertain, part of the consideration can be made contingent on the forecast proving correct.

Market Testing Matters More Than Valuation Theory

Valuation models do not determine what a company will sell for. Buyers do. Different acquirers can assign materially different values to the same business because they are underwriting different economics. Strategic synergies, distribution advantages, acquisition platforms, financing flexibility and divergent views of industry growth can produce different prices from the same financial information. A single buyer's offer is therefore only one buyer's view of value.

A valuation range remains theoretical until the market is tested. One buyer's enthusiasm can weaken during diligence. Several credible buyers provide stronger evidence of where demand actually clears.

Competition can also affect more than headline price. It may influence cash paid at closing, earnout terms, rollover requirements, working-capital treatment, indemnification protections and the duration of exclusivity. That leverage often diminishes quickly once a seller commits to one counterparty.

Uncertainty Is Being Priced More Explicitly

The common thread in valuation, diligence and deal structure is uncertainty. Buyers do not ignore what they cannot verify. They discount it, defer payment against it or seek contractual protection from it. Reliable financials, defensible adjustments and credible forecasts make it harder for a buyer to justify a discount.

Weak financial reporting can become a valuation issue. Aggressive EBITDA adjustments can become a credibility issue. Unsupported projections can become an earnout. Customer concentration can become a purchase-price discount. Heavy owner dependence can become a transition obligation.

The timing of disclosure matters as well. A weakness identified before a process begins can often be addressed or incorporated into positioning. The same weakness discovered late in diligence may become leverage for a buyer that already has exclusivity.

That dynamic helps explain why some transactions deteriorate between the letter of intent and closing. Sellers often negotiate the headline valuation before the buyer has completed its most detailed examination of the business. In M&A, uncertainty is priced or allocated.

Company Timing Can Matter More Than Market Timing

Owners considering a sale naturally ask whether the market will be better six months or a year from now.

Perhaps. The more important question is whether the company will be. A business with accelerating earnings, stronger margins and a developing management team may create substantial value by waiting. A business approaching the loss of a major customer, a cyclical slowdown or a difficult owner transition may not have the same luxury.

A modest improvement in financing conditions will not compensate for deteriorating earnings. Conversely, selling into an active market may still be premature if another year of performance would materially improve the company's financial profile.

Axial's survey illustrates the difficulty of waiting for clarity. Roughly two-thirds of respondents expected political and economic uncertainty to have about the same effect on transaction activity during the second half of 2026 as during the first.[3]

Waiting for better conditions can be rational. The best time to sell is never determined by the market alone. It is when the company's performance, competitive position, owner objectives and external environment align favorably enough to outweigh the cost of waiting.

A More Discriminating M&A Market

The 2026 M&A market does not appear short of buyers or capital. It does appear less tolerant of uncertainty. High-quality companies can still command strong competition and attractive valuations.

Selectivity should not be confused with weakness. For well-positioned businesses, continued buyer competition can still support attractive valuations and favorable terms. The difference is that those outcomes are increasingly earned rather than assumed.


Sources

[1] PwC, U.S. Deals 2026 Midyear Outlook. U.S. announced M&A activity and deal-value data through the first five months of 2026.

[2] Boston Consulting Group, Global M&A Outlook, 2026. Analysis of first-half 2026 global transaction activity and the concentration of the recovery.

[3] Axial, Lower Middle Market M&A Outlook: 2H 2026. July 2026 survey of 79 lower-middle-market buyers and M&A advisors regarding deal activity, buyer competition, valuation, failed transactions and market conditions.

[4] SRS Acquiom, 2026 Lower Middle Market Deal Terms Study. Analysis of earnouts and other transaction terms in smaller private-company acquisitions.

Jul 30

Understanding Working Capital Adjustments in Middle-Market M&A

Versailles Group July 30, 2026

Business owners often focus on the price stated in a letter of intent. That figure is important, but it does not necessarily equal the amount ultimately received. Cash, debt, transaction expenses, escrows, financing terms, and working capital can all affect the bridge from enterprise value to seller proceeds.

Because the working capital target can materially influence that bridge, owners should understand the company’s historical position before accepting the economic terms of an offer.

Why Working Capital Matters in a Sale

Many acquisitions are negotiated on a cash-free, debt-free basis. Under this structure, cash and funded debt are accounted for separately from enterprise value. Depending on the agreement, cash may be distributed before closing or added to the consideration, while debt generally reduces the amount payable to the seller.

The buyer also expects to receive a company that can continue operating in the ordinary course.

Consider a distributor that relies on inventory to fill orders, receivables that will convert into cash, and customary payment terms from suppliers. If the seller collects an unusual amount of receivables, reduces purchases, or delays vendor payments before closing, the company may transfer with less operating capital than it has historically carried.

The buyer may then need to contribute cash shortly after the acquisition to restore normal operations.

In transactions that use a closing-accounts mechanism, the parties typically establish a working capital target, often called the peg. The company’s closing balance is compared with that benchmark. A shortfall may reduce the consideration, while an excess may increase it, depending on the purchase agreement.

The mechanism does not ordinarily reopen the negotiated enterprise value. Instead, it adjusts the consideration to reflect the operating assets and liabilities delivered at closing.

Other transaction structures, such as a locked-box arrangement, may address working capital differently and may not involve a conventional post-closing true-up.

What Counts as Working Capital?

In accounting, working capital is commonly described as current assets minus current liabilities. In an acquisition, the definition is narrower and negotiated.

The calculation may include trade receivables, inventory, certain prepaid expenses, accounts payable, accrued payroll, and other operating liabilities. Cash, funded debt, income taxes, seller transaction expenses, shareholder loans, and related-party balances are often excluded or addressed elsewhere in the purchase-price formula.

The structure of the transaction also matters. In a stock sale, the buyer generally acquires the company with its existing balance-sheet accounts, subject to negotiated adjustments. In an asset purchase, the parties determine which receivables, inventory, prepayments, payables, and accruals will transfer.

A balance classified as working capital in one deal may be treated as debt, a retained liability, or a separate deduction in another. The transaction documents should align the definition with the assets acquired and obligations assumed.

How the Target Is Established

Historical monthly balances, often covering at least one full operating cycle, commonly provide the starting point for the peg. The selected period and methodology, however, depend on the business and the transaction.

The analysis may need to account for seasonality, recent growth, changes in customer or supplier terms, new facilities, product launches, acquisitions, discontinued operations, or unusual balances.

Suppose a manufacturer builds inventory ahead of its busiest quarter. Its annual average includes both high and low points in the production cycle. If the transaction closes shortly before peak demand, the company may ordinarily carry more inventory and receivables than the average suggests.

The benchmark should reflect the company’s normalized working capital requirements, taking its operating cycle and anticipated closing date into account. Historical results remain important, but they may need to be adjusted for identifiable changes that the buyer and seller agree are relevant.

The same account definitions, classifications, reserve policies, and accounting methods should then be applied when calculating the closing balance. Changing the methodology after the target has been established can distort the comparison and shift value between the parties.

From Enterprise Value to Seller Proceeds

Assume a company is valued at $25 million. At closing, it has $500,000 of cash, $3 million of funded debt, $400,000 of seller transaction expenses, and a $400,000 working capital shortfall. The estimated calculation would be:

Purchase-price bridge Amount
Enterprise value $25,000,000
Plus: cash included in the closing calculation $500,000
Less: funded debt ($3,000,000)
Less: seller transaction expenses ($400,000)
Less: working capital shortfall ($400,000)
Estimated consideration before other closing items $21,700,000


The company is still valued at $25 million. The amount payable is lower because enterprise value and seller proceeds are different measures. Other terms may further affect the final result, including escrows, holdbacks, rollover equity, seller notes, earnouts, and taxes.

Many mechanisms provide dollar-for-dollar adjustments in both directions. Others may be one-way or include thresholds, collars, caps, or escrow arrangements. Owners should understand how the provision treats both an excess and a shortfall.

Where Negotiations Commonly Arise

The formula is usually straightforward. The more difficult questions concern how the underlying accounts are measured and classified.

Receivables: Are the recorded balances likely to be collected, and are reserves calculated consistently? Overdue invoices, customer disputes, credits, claim denials, and historical collection patterns may affect the amount included. The closing statement should use the reserve methodology specified in the agreement and applied when the peg was established.

Inventory: Is the stock usable and properly valued under the agreed framework? Manufacturing and distribution companies may face questions involving obsolete, excess, damaged, or slow-moving items. Unless the parties expressly agree otherwise, the closing calculation is generally not intended to become a new fair-value assessment based on the buyer’s post-acquisition plans.

Accrued liabilities: Have obligations relating to the pre-closing period been fully recorded? Bonuses, commissions, payroll taxes, vacation, freight, rebates, and vendor invoices may be incurred before completion but paid afterward. Omitting those amounts can overstate the working capital delivered.

Classification: Is an item being treated as working capital, debt, a transaction expense, or another deduction, and is it being counted more than once? Customer deposits, deferred revenue, related-party balances, unpaid taxes, and committed capital expenditures may require specific treatment. The same economic exposure generally should not reduce consideration more than once, whether through working capital, debt, transaction expenses, or indemnification, unless the agreement expressly provides otherwise.

Working capital can be negative.
Some businesses collect customer payments before paying suppliers or completing the related work. Subscription companies, prepaid service businesses, and companies that receive deposits may therefore operate with negative net working capital. A negative peg is not necessarily a sign of weakness. The relevant question is whether the closing balance is above or below the agreed benchmark.

How the True-Up Is Completed

The amount used at closing is often an estimate because the company’s books cannot always be finalized on the transaction date.

Because the books cannot always be finalized on the transaction date, the initial adjustment is usually based on an estimate. The agreement specifies who prepares that estimate and the post-closing calculation, as well as the seller’s review and objection rights.

The contractual closing statement should also be distinguished from the buyer’s purchase accounting. Unless permitted by the purchase agreement, fair-value adjustments or new reserve assumptions recorded for the buyer’s financial reporting should not be introduced into the closing calculation.

The Industry Shapes the Analysis

The accounts that matter most depend on the company’s operating model.

Manufacturers and distributors tend to focus on inventory, receivables, freight, rebates, and supplier accruals. Construction companies may place greater weight on work in process, billing positions, retainage, and estimated costs to complete. Healthcare providers often examine payer mix, claim status, denials, and contractual allowances.

Staffing firms may carry little inventory but still require substantial operating capital because payroll is funded before customers pay. Subscription businesses frequently negotiate the treatment of deferred revenue, customer prepayments, and implementation obligations.

The methodology should follow the economics of the company rather than a generic template.

What Owners Should Do

Owners and their advisors should analyze historical working capital before signing a letter of intent. The LOI may not establish the final peg or detailed definition, but it should avoid assumptions that could materially alter the economics of the offer.

Before the purchase agreement is signed, the parties should resolve the target, included accounts, accounting policies, and true-up procedures.

A practical review should include:

  • Monthly balance-sheet trends over a full operating cycle
  • Receivable aging, inventory, payables, and major accruals
  • Seasonal patterns and recent operational changes
  • Debt-like, nonoperating, and related-party balances
  • Consistency between the proposed peg and historical accounting practices
  • The bridge from enterprise value to expected proceeds

Operational decisions made before closing should also be considered in light of the adjustment.

Accelerating collections, reducing purchases, or delaying vendor payments may increase cash temporarily. If those actions lower the working capital delivered by the same amount, the benefit may be offset through the closing calculation.

Look Beyond the Headline Price

The practical lesson is straightforward: an offer should be evaluated based on the proceeds it is expected to produce, not enterprise value alone.

That requires understanding the company’s operating cycle, testing the proposed peg against historical balances, and resolving how key balance-sheet accounts will be treated before the transaction documents are finalized.

When those issues are addressed early, the mechanism can operate as intended: a fair reconciliation of the operating assets and liabilities delivered with the business, rather than a source of avoidable disagreement after the headline price has been negotiated.

Jul 09

M&A Services for Founder-Led Businesses: 10 Things to Know in 2026

Versailles Group July 9, 2026

For many founder-led business owners, the first serious M&A conversation begins before a formal decision to sell. It may start with an inbound buyer inquiry, a succession planning question, a desire to take chips off the table, or the realization that the company may need a strategic or financial partner for its next stage of growth.

Why M&A Advisory Services Matter in 2026

The 2026 M&A market remains active.  PwC’s 2026 mid-year outlook indicates that global M&A value is on track to reach approximately $4 trillion.  According to Deloitte, 90% of private equity respondents and 80% of corporate respondents expected an increased number of deals in 2026. Similarly, 87% of private equity respondents and 81% of corporate respondents expected aggregate deal value to increase.

For founder-led businesses, this means the market is favorable, but preparation is still critical. A well-structured M&A process helps owners get ready before going to market, respond strategically to inbound interest, and avoid entering exclusivity before fully understanding the key terms.

Below are 10 things founder-led business owners should know about M&A advisory services in 2026.

1. Founder-Led Businesses Require Specialized M&A Advisory Services

Founder-led businesses often have qualities buyers value: entrepreneurial culture, customer loyalty, specialized expertise, long-standing relationships, and a clear company identity. However, those same qualities can also raise buyer questions.

Potential buyers may ask:

  • How dependent is the business on the founder?
  • Can customer relationships transfer smoothly after closing?
  • Is there a management team capable of operating the business independently?
  • Are systems, reporting, and processes institutionalized?
  • Will the founder remain involved after the transaction?
  • How much growth depends on the founder’s personal relationships?

These questions do not necessarily reduce value, but they must be addressed thoughtfully. Experienced M&A firms help position founder-led companies by explaining not only what the business has achieved, but also how it can continue to grow under new ownership.

In many founder-led transactions, the key issue is whether the process gives the founder enough leverage, buyer options, and deal certainty to make an informed decision.

2. M&A Advisory Services Help Founders Understand What the Business May Be Worth

One of the first questions most founders ask is: “What is my business worth?”

A qualified M&A advisor helps answer that question with market-based analysis rather than guesswork. Valuation support may include reviewing historical financial performance, adjusted EBITDA, revenue trends, gross margins, customer concentration, management depth, industry outlook, comparable transactions, and potential buyer synergies.

For founder-led businesses, valuation is not only about last year’s earnings. Buyers also evaluate whether the business is transferable, scalable, defensible, and capable of performing after the founder steps back.

Important valuation factors may include:

  • Revenue growth and quality of revenue
  • Adjusted EBITDA and margin trends
  • Recurring or repeat customer revenue
  • Customer concentration
  • Supplier concentration
  • Management team strength
  • Sales pipeline visibility
  • Industry growth prospects
  • Intellectual property or proprietary processes
  • Founder dependency
  • Financial reporting quality
  • Potential strategic buyer synergies

For example, two companies with similar EBITDA may receive different valuations if one has recurring revenue, lower customer concentration, stronger second-level management, and cleaner financial reporting.

A founder may think about value based on years of effort and personal commitment. Buyers typically think about value based on risk, future cash flow, growth potential, and strategic fit. Strong M&A advisory services help bridge that gap.

3. Preparation Before Buyer Outreach Can Improve the Sale Process

Many founders wait until they are ready to sell before preparing the business for buyer review. In practice, preparation before buyer outreach can materially improve the quality of the M&A process.

Before approaching buyers, an advisor may help the founder organize financial statements, normalize earnings, prepare add-back schedules, identify diligence issues, review customer data, develop growth narratives, and prepare confidential marketing materials.

This preparation often includes a confidential information memorandum, or CIM, that explains the company’s history, operations, financial performance, market position, customer base, management team, and growth opportunities.

For founder-led businesses, preparation should also address transition planning. Buyers will want to understand what happens after closing. For example:

  • Will the founder remain with the company for a transition period?
  • Is the second-level management team ready for more responsibility?
  • Are key customer relationships held by the founder or by the broader organization?
  • Are operating procedures documented?
  • Are financial reports and KPIs buyer-ready?

Preparation gives buyers confidence. It also helps the founder avoid answering difficult questions for the first time during diligence, when leverage may already be shifting toward the buyer.

4. A Strong M&A Advisor Helps Position the Company’s Story

A founder knows the company better than anyone. However, the founder’s story still needs to be translated into a format that buyers, lenders, investors, and acquisition committees can evaluate.

This is where M&A advisory services become especially important. A strong advisor helps convert the founder’s knowledge into a clear investment thesis.

That may include explaining:

  • Why the company has grown
  • What makes the business defensible
  • Why customers choose the company
  • How the business compares to competitors
  • Where future growth may come from
  • Why the company is attractive to strategic or financial buyers
  • How the business can succeed beyond the founder

For example, a founder may say, “Our customers trust us because we have been in the industry for 30 years.” An advisor may help translate that into a buyer-focused message: “The company benefits from long-standing customer relationships, high repeat business, and a reputation for technical expertise in a specialized market.”

That distinction matters. Buyers assess not only past performance, but also the future.

5. Buyer Outreach Should Be Targeted, Confidential, and Competitive

The best buyer is not always the buyer with the highest initial indication of value. Founder-led business owners may also care about certainty of closing, employee treatment, cultural fit, strategic rationale, financing capability, and the founder’s post-closing role.

This is especially important when a founder has already received inbound interest. A single buyer may be serious, but a single conversation does not establish market value. Without a broader process, the founder may not know whether other buyers would value the business more highly, offer better terms, or provide greater certainty.

An experienced advisor may identify several categories of potential buyers, including:

  • Strategic acquirers
  • Competitors
  • Suppliers or customers
  • Private equity firms
  • Private equity portfolio companies
  • Family offices
  • Independent sponsors
  • Search funds
  • International buyers

Experienced M&A firms help founder-led businesses reach a broader universe of qualified buyers while maintaining control over confidentiality, messaging, and timing.

6. Confidentiality Is Central to Protecting the Business

Confidentiality is one of the most important concerns in founder-led M&A.

If employees, customers, competitors, suppliers, or lenders learn about a potential transaction too early, it can create confusion and risk. Even a well-intentioned buyer inquiry can become disruptive if it is not managed carefully.

M&A advisory services often include confidentiality protections such as:

  • Anonymous teaser materials
  • Non-disclosure agreements
  • Controlled buyer lists
  • Staged information sharing
  • Secure data rooms
  • Process letters
  • Limited access to sensitive customer or employee information
  • Careful timing around management meetings and site visits

For founders, confidentiality protects employees, customer relationships, competitive position, and negotiating leverage. A founder should understand exactly how an advisor will protect sensitive information before any buyer outreach begins.

7. Deal Structure Can Matter as Much as Purchase Price

Founders often focus on valuation. However, deal structure can materially affect actual economics, risk, tax impact, and post-closing obligations.

Two offers with similar purchase prices can produce very different outcomes. Important deal structure considerations may include:

  • Cash paid at closing
  • Seller financing
  • Earnouts
  • Equity rollover
  • Working capital adjustments
  • Escrows and holdbacks
  • Asset sale versus stock sale
  • Employment or consulting agreements
  • Non-compete provisions
  • Transition support
  • Tax considerations

For example, a founder may receive one offer at a higher valuation with a significant earnout and another offer at a slightly lower valuation with more cash paid at closing. The higher headline price may not be the better offer if the earnout depends on aggressive future performance targets outside the founder’s control.

Working capital can also materially affect proceeds. A buyer may agree to a purchase price but later negotiate a working capital target that reduces cash received at closing. Similarly, escrow, indemnity, rollover equity, and financing conditions can change the real risk profile of a transaction.

An M&A advisor helps compare offers based on total value, certainty, timing, structure, contingencies, and post-closing obligations. Legal and tax advisors should also be involved before a founder agrees to final transaction terms.

8. Founders Should Be Careful Before Signing an LOI

The letter of intent, or LOI, is one of the most important stages in a sale process.

An LOI may appear preliminary, but it often sets the economic and procedural framework for the rest of the transaction. Once a founder signs an LOI and grants exclusivity, leverage often shifts toward the buyer. At that point, the seller may be limited in the ability to speak with other buyers while the selected buyer completes diligence, arranges financing, and negotiates definitive agreements.

Before signing an LOI, founders should understand:

  • Purchase price and form of consideration
  • Cash at closing
  • Earnout terms
  • Rollover equity requirements
  • Working capital expectations
  • Escrow or holdback requirements
  • Exclusivity period
  • Financing conditions
  • Key diligence conditions
  • Expected closing timeline
  • Post-closing employment or consulting obligations
  • Non-compete and restrictive covenant expectations

A strong M&A advisor helps founders evaluate not only whether the headline offer is attractive, but also whether the LOI terms preserve leverage and reduce the risk of retrading later in the process.

9. Founders Should Understand the Difference Between M&A Firms, Business Brokers, and Acquisition Consultants

Business brokers can be appropriate for smaller, owner-operated businesses where the buyer universe is more local and the transaction process is less complex.

Acquisition consultants may help buyers identify acquisition targets or develop buy-side growth strategies.

M&A firms and investment banks typically advise on more complex middle-market transactions that may involve valuation analysis, confidential buyer outreach, competitive process management, negotiation, due diligence coordination, and deal structuring.

For founder-led middle-market businesses, the right advisor often depends on transaction size, business complexity, buyer universe, confidentiality needs, and owner objectives.

When evaluating M&A advisory services, founders should ask:

  • Does the advisor have experience with middle-market business sales?
  • Has the advisor worked with founder-led or entrepreneur-owned businesses?
  • How will the advisor estimate valuation?
  • How will the advisor identify potential buyers?
  • How will confidentiality be protected?
  • Who will actually manage the transaction day to day?
  • How will buyer communications be handled?
  • How will competing offers be compared?
  • What transaction experience does the advisor bring to negotiations?

The goal is to hire an advisor who understands the founder’s business, timeline, concerns, and desired outcome.

10. The Right Advisor Helps Founders Avoid M&A Mistakes

Many founders only sell a business once. Buyers, especially private equity firms and experienced strategic acquirers, may evaluate acquisitions regularly. That experience gap can create risk.

Common mistakes founders should avoid include:

  • Speaking with only one buyer without testing broader market interest
  • Sharing confidential information too early
  • Going to market before financial information is prepared
  • Accepting a valuation indication without understanding structure
  • Focusing only on the multiple instead of net proceeds
  • Underestimating due diligence
  • Overlooking customer concentration or management succession issues
  • Failing to prepare for working capital negotiations
  • Signing an LOI before understanding exclusivity and contingencies
  • Waiting too long to plan for ownership transition
  • Choosing an advisor based only on fees

A strong M&A advisor helps founders anticipate issues before they become costly. The advisor’s role is not only to market the company, but also to manage the process, protect leverage, evaluate buyers, and help the founder make informed decisions.

In many cases, the quality of the process can affect the quality of the outcome.

Considering a Sale?

A business owner does not need to be ready to sell tomorrow before speaking with an M&A advisor. In fact, early guidance can be valuable. If you are evaluating inbound buyer interest, considering a sale, or planning for a future ownership transition, we would welcome the opportunity to discuss valuation, buyer appetite, timing, and potential transaction alternatives.

Request a Session >>


Frequently Asked Questions

What are M&A advisory services?

M&A advisory services help business owners evaluate, prepare for, and execute mergers and acquisitions transactions. For sellers, this often includes valuation analysis, preparation of marketing materials, buyer identification, confidential outreach, negotiation, due diligence coordination, and closing process support.

When should a founder hire an M&A advisor?

A founder should consider speaking with an M&A advisor when evaluating a sale, receiving inbound buyer interest, planning for retirement or succession, considering a recapitalization, or seeking to understand valuation and market interest. Early guidance can help the founder prepare before launching a formal process.

Do I need an M&A advisor if I already have an offer?

An advisor can help determine whether the offer reflects market value, whether the structure is favorable, and whether other buyers may have stronger interest. A single offer may be attractive, but it does not necessarily show what the broader market would pay.

What is the difference between an M&A advisor and a business broker?

Business brokers typically focus on smaller business sales, while M&A advisors and investment banks often work on more complex middle-market transactions. 

How do M&A firms find buyers?

M&A firms typically identify buyers through industry research, transaction databases, private equity relationships, strategic acquirer mapping, portfolio company analysis, prior transaction experience, and targeted outreach. The goal is to create a qualified buyer universe that includes both strategic and financial buyers.

How long does it take to sell a middle-market business?

The timeline varies based on preparation, buyer interest, diligence, financing, negotiation, and transaction complexity. Many middle-market sale processes take several months from preparation through closing, and complex transactions may take longer.

How important is confidentiality in the M&A process?

Confidentiality is extremely important, especially for founder-led businesses. A well-managed process protects sensitive information through anonymous teasers, non-disclosure agreements, staged information sharing, secure data rooms, and careful communication protocols.


Jun 09

What Buyers Really Look for in a Niche Market Company

Donald Grava June 9, 2026

Photograph showing a close-up view of lake surface with gentle ripples reflecting light. The water appears calm with varying shades of blue and dark green.

In a sale process, a niche market can be a constraint or a source of premium value. Buyers don’t discount a company because it serves a narrow market, but they do when that narrowness can’t translate into transferable relationships or credible growth. Sometimes, owners assume specialized companies are harder to sell, but buyers may see the opposite. A focused company with loyal customers, specialized expertise, and a defensible position can be more attractive than a broader business with weaker differentiation.

The question is whether that niche creates durable value.  A niche company can draw strong buyer interest when its focus produces pricing power, repeat demand, customer loyalty, technical credibility, or barriers to entry. Its narrowness often makes it difficult to replace, as it may understand a customer segment better, operate in a specialized market that supports consistent earnings, or own a position that would take years to build internally.

What Market Does This Company Really Own?

The first question buyers ask is often foundational: what market is this company actually in? For many niche businesses, the answer is not immediately obvious. The company may not fit neatly into a standard industry category. Its customers may use specialized terminology. Its products or services may solve a problem that is highly important to a narrow group of customers but unfamiliar to outsiders.

Buyers need to understand who the customers are, what problem the business solves, how purchasing decisions are made, and why the company’s role matters. They also need to understand the size and character of the opportunity. The niche does not have to be enormous, but it must be meaningful enough to support continued growth or stable cash flow.

This is where some sellers weaken their story. In an effort to appear more scalable, they define the market too broadly. A specialized manufacturer serving a regulated medical, aerospace, or industrial application may try to present itself as part of a much larger manufacturing market. A narrowly focused B2B services firm may describe its opportunity in terms of a broad professional-services category. Buyers usually recognize the difference. They are more persuaded by a precise market definition than by an inflated addressable market that does not reflect how customers actually buy.

A niche company needs to show that the market it serves is real, economically meaningful, and difficult for less-specialized competitors to penetrate.

Why Does the Company Win?

Once buyers understand the market, they turn to a more important question: why does this company win? A niche position has limited value if it is based only on being early, local, or familiar. Buyers want evidence that the company’s advantage is durable.

The strongest niche companies do not merely participate in a narrow market. They have earned a position within it. Customers may rely on them because mistakes are costly, service quality matters, compliance requirements are demanding, or switching vendors would create operational risk. A medical component supplier, for example, may be valuable not simply because it produces a specialized part, but because it is already qualified within customer programs where changing suppliers would require testing, documentation, and risk review. A specialized business-services provider may be difficult to replace because its team understands a workflow that generalist competitors cannot easily staff, manage, or replicate.

Buyers will test these claims. They will look at customer retention, pricing history, gross margins, win rates, customer references, and competitive alternatives. They will ask whether customers choose the company because it is truly differentiated or because there have been few alternatives in the past. They will also examine whether the company’s advantage is recognized by the market or simply asserted by management.

Saying the company is “highly specialized” is not enough. Buyers need to understand what that specialization does. Does it reduce customer risk? Does it solve problems faster? Does it meet standards others cannot? Does it combine responsiveness, expertise, and customization in a way larger competitors struggle to match?

How Durable Are the Earnings?

Profitability matters, but durability determines how buyers underwrite value. This is especially important for niche market companies, where earnings may depend on a specific group of customers, a limited set of suppliers, a specialized labor pool, or the personal involvement of the founder.

Customer concentration is often a central issue. Many niche companies have a small number of large customers, and that is not automatically a problem. A concentrated customer base can still be attractive if the relationships are long-standing, the work is recurring, and the company is deeply embedded in the customer’s operations. But buyers will want to understand the risk. If one customer represents a meaningful share of revenue, they will ask how long the relationship has existed, who owns it, whether contracts are in place, and how likely the customer is to remain after a transaction.

Margins also need explanation. Strong margins can be a powerful signal, but buyers will want to know what drives them. Are they the result of pricing power, operational efficiency, specialized expertise, or limited competition? Or are they inflated because the company has underinvested in sales, technology, management, or infrastructure?

A business with strong margins, repeat demand, and clear pricing power may be viewed as a high-quality earnings stream. A business with similar EBITDA but weak systems, customer concentration, or heavy owner dependency may still attract interest, but buyers may discount the value, require more diligence, or seek protection through structure.

Historical EBITDA matters most when buyers can connect it to repeatable demand, stable margins, and customer relationships that are likely to survive a change in ownership.

Can the Business Grow Beyond Its Current Base?

Growth does not have to mean abandoning the niche. In many cases, the strongest growth strategy is to deepen or extend the company’s existing position rather than reposition the business around a broader, less credible market.

The best growth stories are usually adjacent. Buyers are more likely to believe expansion into a related geography, customer segment, product category, or service line than a strategy that requires the company to become something fundamentally different. A niche manufacturer may have grown largely through referrals and long-standing accounts, leaving room for a more deliberate sales effort. A specialized services company may already be asked by customers to handle adjacent needs but may not yet have the staff, systems, or capital to capture that demand.

Buyers are skeptical of vague growth claims. Phrases such as “large untapped market” or “significant growth potential” do little on their own. Buyers want to understand the specific actions that could drive growth, the investment required, the likely timeline, and the risks involved. A credible growth story is grounded in evidence: customer requests, historical expansion patterns, fragmented competition, underdeveloped sales channels, or capacity constraints that can be addressed.

For a strategic buyer, growth may come from combining the niche company with an existing platform. The buyer may bring a larger sales force, broader distribution, complementary products, or access to customers the seller could not efficiently reach alone. For a financial buyer, growth may come from strengthening management, improving reporting, investing in systems, and using the company as a platform for add-on acquisitions.

The key is to show that growth is available without undermining the company’s core advantage. Buyers are not looking for a niche business to suddenly become a generalist. They are looking for a focused company whose capabilities can support a larger opportunity.

Will the Value Transfer After Closing?

Buyers will ask how much of the company’s value depends on the owner personally. Does the founder control the key customer relationships? Are technical decisions documented or informal? Can the management team operate independently? Would employees, customers, and suppliers remain confident after a change in ownership?

Owner dependency is not fatal. Many successful transactions involve founder-led companies where the owner remains involved for a transition period. But buyers need to understand whether the business can eventually stand on its own. The more specialized the company, the more important this becomes. If the knowledge, relationships, and operating judgment are concentrated in the founder, buyers may view the business as riskier than its financial statements suggest.

This risk can affect more than buyer interest. It can affect valuation, deal structure, and closing certainty. A buyer concerned about transferability may seek a longer transition period, seller financing, an earnout, customer-retention conditions, or a lower purchase price. Conversely, a company with a capable management team, documented processes, distributed customer relationships, and reliable reporting is easier for buyers to underwrite.

In most successful founder-led companies, the founder has been essential. The issue is whether the company’s value has become institutional rather than purely personal.

Why Would This Matter to a Strategic or Financial Buyer?

For strategic buyers, niche companies can provide capability, access, or fit. A buyer may be looking for specialized technical talent, a respected brand, a difficult-to-enter customer base, a complementary product line, or a foothold in a specific vertical. Even if the company is not large, it may solve a strategic problem the buyer cannot solve quickly on its own.

In those cases, the company’s value may go beyond its standalone earnings. It may help the buyer enter a market, strengthen a product offering, serve existing customers more completely, or acquire expertise that would take years to build internally. Strategic buyers often care deeply about whether the niche company strengthens their broader competitive position.

Financial buyers evaluate the opportunity differently. They usually need a clearer underwriting case. They may appreciate the niche, but they are generally less willing than a strategic buyer to pay for vague market access or speculative synergies. They will focus on whether the company can produce repeatable cash flow, support leverage, scale beyond the founder, and serve as a platform or attractive add-on within a broader investment strategy.

Both buyer types are asking a version of the same question: why should this company be worth more with a new owner than it is on its own? The seller does not need to invent speculative synergies. But it does need to understand the company’s strategic relevance and present it clearly.

A niche company commands stronger interest when buyers see not only what the business is today, but also why it would be difficult, expensive, or time-consuming to recreate.

The Real Focus

The best niche market companies do not try to hide their specialization. They show buyers what market they own, why customers rely on them, how their earnings are produced, where growth can come from, and how the company can transition after closing.

For owners, the implication is important. Preparing a niche company for buyer review is about making the value of its focus clear. Buyers need to believe that the company’s position is real and its opportunity is credible. In M&A, the companies that receive the strongest buyer interest are often the ones that can explain why they own a valuable place in the market and why they are difficult to replace.


Speak Confidentially with Versailles Group

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

If you are considering selling or acquiring a company, we welcome the opportunity to discuss your objectives and offer a clear perspective on your options.

Request a Session >>


May 19

What EBITDA Actually Tells a Buyer About Your Business

Donald Grava May 19, 2026

Chicago street view

For many business owners and founders, EBITDA becomes shorthand for value. If a company generates $5 million of EBITDA and comparable businesses trade near six times EBITDA, the implied valuation appears straightforward: $5 million multiplied by six equals $30 million of enterprise value.

In a real sale process, that calculation is only the beginning. Two companies with the same EBITDA can receive very different offers. One may attract a strong valuation, meaningful cash at closing, and clean terms. Another may face a lower multiple, a larger escrow, a seller note, an earnout, or a more difficult diligence process. The difference is not simply the amount of EBITDA. It is the buyer’s confidence in the business behind the number.

In middle-market M&A, buyers do not pay for EBITDA in isolation. They pay for earnings they believe can continue under new ownership. The stronger that belief, the stronger the support for valuation, deal certainty, and favorable terms. The weaker it is, the more likely the buyer is to reduce value, increase diligence, or shift risk back to the seller.

EBITDA Is the Starting Point, Not the Answer

EBITDA, or earnings before interest, taxes, depreciation, and amortization, is widely used in M&A because it helps compare companies with different debt levels, tax profiles, depreciation policies, and ownership histories. By removing certain items that may not reflect core operating performance, EBITDA gives buyers an initial view of profitability.

Its usefulness can also create a misconception. Because EBITDA is often tied to valuation multiples, owners may treat it as the answer to the valuation question. In reality, it is only the beginning of the analysis. Once the headline number is established, the more important questions begin. Is the EBITDA normal? Is it repeatable? Does it convert into cash? Can it survive the founder’s transition out of the business? Can it be proven in diligence?

A company that produces $5 million of EBITDA through recurring customers, disciplined pricing, stable margins, and capable management will be viewed differently from a company that reaches the same number through a temporary demand spike, delayed expenses, or one unusually profitable project. Both companies may report the same EBITDA, but the risk profile behind the earnings is different.

That distinction matters because valuation multiples reflect risk. A premium multiple is rarely paid for EBITDA alone. It is paid for EBITDA that supports a credible investment case.

Adjusted EBITDA Is a Credibility Test

In most middle-market transactions, the discussion quickly moves from reported EBITDA to adjusted EBITDA. Sellers often adjust for expenses that are unusual, non-recurring, discretionary, or not expected to continue under new ownership. Common examples include excess owner compensation, personal expenses run through the business, one-time legal costs, unusual consulting fees, discontinued business lines, non-recurring repairs, or expenses tied to a resolved event.

These adjustments can be legitimate and important. Many founder-led companies do not operate with the same expense structure an institutional buyer would expect after closing. A founder may take compensation above or below market. The company may have incurred professional fees related to a specific issue. Certain discretionary expenses may not be necessary going forward. Properly presented, adjusted EBITDA can provide a clearer view of normalized earnings.

But every adjustment is also a request for trust. An addback will not be accepted simply because it appears in a schedule. It must be supported by facts. Was the expense truly non-recurring? Is there documentation? Was it necessary to operate the business? Could a similar cost appear again?

For example, a legal expense tied to a resolved shareholder dispute may be accepted if there is a signed settlement agreement and no continuing exposure. If legal expenses appear every year, however, a buyer may treat them as part of the normal cost of running the business. A one-time consulting fee may be accepted if it supported a completed system implementation. But if the company regularly uses outside consultants to perform work that internal management cannot handle, the cost may not be viewed as temporary.

This is why adjusted EBITDA is not merely a mathematical exercise. It is a credibility test. A well-supported adjustment schedule can strengthen the seller’s position because it shows that management understands the numbers and is presenting them responsibly. An aggressive or poorly supported schedule can have the opposite effect. Even if the business is attractive, weak addback support can make the broader earnings story less believable.

The Same EBITDA Can Carry Very Different Risk

Buyers care not only about how much EBITDA a business generates, but also how that EBITDA is produced. They want to understand the source, durability, and concentration of earnings. That requires analysis by customer, product line, service category, geography, channel, contract type, and margin profile.

Consider two businesses that each generate $5 million of EBITDA. The first has recurring revenue, strong customer retention, diversified accounts, stable gross margins, clean monthly reporting, modest capital expenditure needs, and a management team that can run the company without the founder’s daily involvement. The second generates the same EBITDA from a small number of large project-based customers, has inconsistent margins, aging equipment, limited financial controls, and a founder who personally manages the most important commercial relationships.

On paper, both companies show $5 million of EBITDA. To a buyer, they are not the same business. The first company gives the buyer more comfort that earnings will continue after closing. The second may still be attractive, but the risk is higher. If one customer leaves, if the founder steps back, if a major project does not repeat, or if capital expenditures increase, EBITDA could change quickly. That uncertainty may result in a lower multiple, expanded diligence, a longer transition period, or more protective deal terms.

This is why market multiples vary widely. Owners often ask what multiple companies in their industry are receiving. That is a fair question, but it is incomplete without understanding the quality of the earnings. EBITDA supported by recurring customers, pricing power, stable margins, and a scalable operating model is more valuable than EBITDA created by one-off projects, temporary cost reductions, or constant owner intervention.

Growth must be evaluated the same way. Owners often assume that revenue growth increases value. Buyers are more specific. They want to know whether growth is profitable, repeatable, and capital-efficient. A company that grows revenue while maintaining margins, expanding customer relationships, and improving operating leverage will be viewed differently from a company that grows by discounting, accepting lower-quality work, relying on one major customer, or stretching operations beyond capacity.

For example, a company may show margin expansion because it raised prices across a broad customer base while maintaining retention. That is a favorable signal because it suggests pricing power and customer loyalty. Another company may show similar margin expansion because it postponed hiring, delayed equipment maintenance, or benefited from one unusually profitable order. The improvement may look similar in the financial statements, but the quality of that improvement is different.

EBITDA Is Not the Same as Cash Flow

A business can report strong EBITDA while still requiring significant capital expenditures, heavy inventory investment, long collection cycles, or recurring maintenance spending. In those cases, EBITDA may overstate how much cash the business actually produces.

This issue is especially important in capital-intensive industries. A manufacturing company may generate attractive EBITDA but require regular investment in equipment, tooling, facility improvements, repairs, or inventory. If the company increased EBITDA by postponing maintenance or delaying equipment replacement, a buyer will likely treat that improvement with caution. The earnings may be real, but they may not be sustainable without reinvestment.

Working capital can create the same issue. A distribution business may need more inventory and receivables to support growth. A project-based company may show strong earnings but experience uneven cash flow because of milestone billing, retainage, or slow customer payments. A company may look profitable on an income statement while still consuming cash as it grows.

By contrast, a services business with recurring contracts, limited capital expenditure needs, strong collections, and low working capital requirements may convert a much higher percentage of EBITDA into cash. That difference affects debt capacity, return on invested capital, and the amount of additional funding required after closing.

This is why buyers study the relationship among EBITDA, capital expenditures, and working capital. They are not only asking what the company earned. They are asking how much cash the business produced and how much cash it will require in the future.

Founder Dependency Affects the Transferability of EBITDA

For founder-led companies, EBITDA also raises a question of transferability. A business may produce strong earnings, but a buyer will want to know how much of that performance depends on the founder personally.

In many middle-market companies, the founder remains central to customer relationships, pricing decisions, employee management, supplier negotiations, technical knowledge, and sales generation. That involvement may be one of the reasons the company has succeeded. It can also create risk if the founder intends to step back after closing.

The concern is straightforward: are the earnings embedded in the company, or are they tied too closely to the seller? If the founder is the primary rainmaker, chief problem solver, and relationship manager, some portion of EBITDA may be viewed as personally attached to that individual rather than institutionally supported by the business.

That does not mean founder-led companies are unattractive. Many are highly valuable because they have strong cultures, loyal customers, and entrepreneurial discipline. The distinction is whether the business can continue to perform under new ownership.

A capable management team, documented processes, delegated customer relationships, reliable reporting, and clear operating systems reduce that concern. They show that the company is not dependent on one person’s daily involvement and that earnings can transfer with the business after a transaction.

Diligence Turns EBITDA Quality Into Deal Terms

Buyers and their advisors will examine financial statements, tax returns, general ledgers, payroll records, customer revenue detail, contracts, margin trends, working capital schedules, and support for addbacks. They will compare the marketing materials against the underlying records. They will test whether management’s explanation of the business is consistent with the data.

This is where conviction can rise or fall quickly. If the EBITDA story presented early in the process is supported by clean data, clear explanations, and consistent documentation, the seller’s credibility improves. Buyers may still negotiate, but they are negotiating against a more reliable fact pattern.

If the EBITDA story weakens during diligence, the consequences can be significant. A buyer may re-trade the price, request additional protection, expand diligence, question management’s credibility, or move more of the purchase price into contingent consideration. In some cases, the buyer may still want the business, but it will no longer be willing to bear the same level of risk.

Owners often focus on purchase price, but buyers express uncertainty in more ways than valuation. A buyer may reduce the upfront purchase price. It may require a larger escrow, a seller note, rollover equity, or an earnout. It may propose a more aggressive working capital target, broader indemnity terms, tighter closing conditions, or a longer transition period for the founder. In each case, uncertainty is being converted into structure, with some portion of the risk shifted back to the seller.

That is why two offers with similar headline values may not be economically equivalent. One buyer may offer a higher stated price but include a large earnout, an aggressive working capital adjustment, a substantial escrow, and uncertain financing. Another may offer a slightly lower price but provide more cash at closing, cleaner terms, stronger certainty, and fewer post-closing contingencies. For a seller, the second offer may be more attractive even if the headline multiple appears lower.

EBITDA quality affects more than the multiple. It influences how much cash is paid at closing, how much value is deferred, and how much risk remains with the seller after the LOI is signed.

The Better Question for Owners

For a founder or CEO considering a sale, the question is not simply, “What is my EBITDA?” The better question is, “How will a buyer interpret my EBITDA?”

That question leads to a more complete assessment of the company. Are earnings recurring? Are margins sustainable? Is customer concentration a material risk? Is growth profitable? Does EBITDA convert into cash? Can management operate without the founder? Can the financial information withstand diligence?

In a well-run sale process, the objective is not to inflate EBITDA. It is to present earnings in a way that buyers can understand, verify, finance, and carry through closing. That requires a clear explanation of the business behind the number, supported by documentation and reinforced through a disciplined process.

This matters especially before exclusivity. Once a seller grants exclusivity to one buyer, competitive tension declines and leverage shifts. If EBITDA has not been properly explained and supported before that point, the seller may be more exposed to price reductions, structure changes, or new diligence demands later in the process.

For owners preparing for a sale, the goal is not simply to present the highest defensible EBITDA number. It is to make the buyer comfortable that the earnings are real, repeatable, transferable, and supported before exclusivity is granted.


About Versailles Group, Ltd.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.


Speak Confidentially with Versailles Group

If you are considering selling or acquiring a company, we welcome the opportunity to discuss your objectives and offer a clear perspective on your options.

Request a Session >>


May 12

The Best M&A Negotiation Happens Before Exclusivity

Gil He May 12, 2026

The Gentlemen Statues in AMA Plaza in Chicago, Illinois

By the time a business owner is comparing offers, the most important negotiation may already be underway. By the time the owner signs a Letter of Intent and grants exclusivity to one buyer, much of the seller’s leverage may already be gone.

That is one of the most misunderstood realities in M&A. Many owners assume negotiation begins when a buyer submits an offer and the banker starts pushing for a higher price. In a properly managed sale process, negotiation starts much earlier. It begins with the design of the buyer list, the positioning of the business, the control of information, the timing of buyer outreach, and the creation of competitive pressure before buyers ever submit a formal proposal.

An effective investment banker does not negotiate by simply demanding a higher number. That is too narrow and often too late. The best bankers create leverage before formal negotiation begins by controlling process, information, timing, buyer psychology, competitive tension, and deal structure. In M&A, the strongest negotiating position is often built quietly, step by step, before the seller selects a preferred buyer.

Negotiation Is Built Into the Process

In M&A, negotiation is not one conversation. It is a sequence of leverage points that unfold across the entire sale process. The buyer list, NDA, Confidential Information Memorandum, management presentation, IOI and LOI comparison, exclusivity period, working capital mechanism, escrow, indemnity provisions, earnout structure, financing certainty, and closing mechanics all influence the seller’s final outcome.

Each stage either strengthens the seller’s position or gives leverage away. A strong buyer list creates alternatives. A weak buyer list limits them. A well-positioned CIM helps buyers understand the strategic value of the company. A generic CIM may cause buyers to focus only on historical earnings. A disciplined process deadline creates urgency. A loose process invites delay.

This is why process design is not administrative work. It is negotiation infrastructure. Before a buyer offers a price, the banker is already influencing how that buyer perceives scarcity, risk, urgency, and competition.

The Buyer List Is the First Negotiation

The buyer list is one of the earliest and most important negotiation decisions in a sale process. A thoughtful list can create competition among strategic buyers, private equity firms, family offices, and other qualified acquirers. A poorly designed list can leave the seller dependent on a narrow group of buyers with similar assumptions, similar valuation frameworks, and limited urgency.

For example, a strategic buyer may be willing to pay more because it can realize synergies, enter a new market, acquire specialized capabilities, or strengthen its customer base. A financial buyer may be more flexible on structure or management continuity. A family office may value long-term ownership and cultural fit. The banker’s job is not simply to contact buyers. It is to identify which buyers have the strongest reason to act and then manage them in a process where they know they are not alone.

Buyers behave differently when they believe they are competing. A buyer with no pressure may ask for more time, more diligence, more protections, and more concessions. A buyer that knows it may lose the opportunity is more likely to sharpen valuation, move quickly through internal approvals, and reduce unnecessary friction.

Price Is Only One Part of Value

Many sellers naturally focus on headline valuation. That is understandable, but it can also be dangerous. The highest number is not always the best deal.

Consider two offers. One buyer offers $50 million, but only $40 million is paid at closing. The remaining $10 million depends on an earnout tied to aggressive future performance. The buyer also requires a large escrow, broad indemnity protections, and third-party financing that has not yet been fully committed. Another buyer offers $47 million, all cash at closing, with a smaller escrow, limited contingencies, and committed financing.

The first offer may look better in a headline comparison. The second may deliver more actual value with far less risk.

A skilled banker evaluates the full economic package, not just the purchase price. Cash at closing, seller notes, rollover equity, earnouts, escrow size and duration, indemnity caps, working capital adjustments, financing certainty, regulatory approvals, and closing conditions all affect the seller’s true outcome. The right question is not simply, “Which buyer offered the most?” The better question is, “Which offer delivers the best combination of value, certainty, timing, structure, and risk allocation?”

That distinction matters because buyers often use structure to protect themselves while preserving the appearance of a strong valuation. A good banker forces buyers to compete not only on price, but also on terms.

Information Control Protects Leverage

Information is one of the most powerful tools in an M&A process. Buyers need enough information to build conviction, but sellers should not release sensitive materials too early or without proper context. Customer names, employee information, pricing data, margin detail, supplier contracts, and operational weaknesses should be handled carefully and released at the appropriate stage.

The objective is not to hide information. The objective is to manage disclosure intelligently. A banker should give buyers what they need to submit serious proposals while protecting confidentiality and preserving leverage for later stages. The timing, sequencing, and framing of information can directly influence buyer confidence and valuation.

For instance, a customer concentration issue may be a legitimate concern. If presented poorly, it can become a reason for a buyer to discount value. If explained properly, with customer tenure, renewal history, switching costs, and relationship depth, the same issue may be understood in context. The facts may not change, but the buyer’s interpretation of those facts can change significantly.

That, too, is negotiation.

The LOI Is Where Leverage Can Shift Quickly

The Letter of Intent is often one of the most important negotiation points in the transaction. It may not be the final purchase agreement, but it sets the framework for price, structure, diligence, financing, timing, working capital, escrow, indemnity expectations, and closing conditions.

Sellers sometimes view the LOI as a preliminary document that can be refined later. That can be a costly mistake. Once the seller signs an LOI and grants exclusivity, the process changes. The seller typically stops active discussions with other buyers. The selected buyer knows it now has a privileged position. The competitive tension that supported the seller’s leverage begins to fade.

That is why the period before exclusivity is so important. Before exclusivity, buyers must compete. After exclusivity, the seller is often negotiating with one buyer. Before exclusivity, the seller can compare alternatives. After exclusivity, the seller may have to choose between accepting a concession or restarting the process. Before exclusivity, the buyer is trying to win the deal. After exclusivity, the buyer is trying to confirm, refine, and sometimes improve its own economics.

A strong banker negotiates the LOI with that shift in mind. The goal is not merely to get a signed LOI. The goal is to secure the right LOI from the right buyer on terms that protect the seller before leverage moves to the other side.

Exclusivity Should Be Earned, Not Given Away

Exclusivity is valuable. Sellers should treat it that way.

When a buyer asks for exclusivity, it is asking the seller to stop using one of the most powerful tools in the process: competition. That request may be reasonable, but it should not be granted casually. Before exclusivity begins, key terms should be as clear as possible, including price, form of consideration, financing certainty, diligence scope, working capital methodology, escrow expectations, indemnity framework, timing to closing, and any major conditions.

If those issues are left vague, the seller may find itself exposed later. A buyer may discover an issue in diligence and seek a price reduction. It may revise the working capital target. It may ask for a larger escrow. It may stretch the timeline. It may introduce new closing conditions. Some of these requests may be legitimate. Others may reflect a buyer testing the seller’s leverage after competition has been removed.

The banker’s job is to reduce that risk before exclusivity is granted. A disciplined process makes the buyer earn exclusivity by submitting a serious, complete, and supportable proposal.

Timing and Momentum Shape Buyer Behavior

Timing is another important negotiation tool. A process that moves too slowly can lose urgency. Buyers may become distracted, financing markets may shift, internal approvals may stall, and diligence fatigue may set in. A process that moves too quickly can also create risk if the seller is unprepared or if buyers do not receive enough information to submit thoughtful proposals.

The banker’s role is to manage timing with discipline. Clear deadlines for IOIs, management meetings, LOI submissions, diligence stages, and final documentation create structure. They also send a message: the seller is prepared, the process is competitive, and buyers are expected to act professionally.

Momentum matters because it affects psychology. A buyer that senses a serious, well-run process will usually behave differently from a buyer that senses confusion, delay, or lack of alternatives. In M&A, process discipline is not just about organization. It creates pressure, and pressure influences terms.

The Best Negotiation Is Often Invisible

The strongest M&A negotiation is not always visible in a single meeting or phone call. It is built through preparation, positioning, process design, and disciplined execution. It happens when the banker anticipates where buyers will apply pressure, prepares the seller for difficult diligence questions, frames risks in proper context, preserves alternatives, and avoids giving away leverage too early.

This is the difference between reactive negotiation and strategic negotiation. Reactive negotiation waits for a buyer to make demands and then responds. Strategic negotiation designs the process so the seller has leverage when those demands appear.

For business owners, the distinction is critical. A successful sale is not won by arguing over price at the end of the process. It is won by building negotiating strength from the beginning. The best bankers understand that value is created not only through valuation, but through competition, certainty, timing, structure, and control.

In M&A, the seller’s strongest leverage is often created before exclusivity. Owners who understand that reality are better positioned to protect value before the balance of power begins to shift.


About Versailles Group, Ltd.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.


Speak Confidentially with Versailles Group

If you are considering selling or acquiring a company, we welcome the opportunity to discuss your objectives and offer a clear perspective on your options.

Request a Session >>