Jun 18

Why Versailles Group Recommends M&A Versus an IPO

Donald Grava June 18, 2015

why versailles group recommends M&A versus an IPO

A business owner seeking to take advantage of his or her company’s value will often consider two options for cashing out—an M&A event or an IPO. Before commencing either process, the business owner should weigh the relative pros and cons of both options as they pertain to his or her goals. An IPO is a financing event that recapitalizes the company, while a company sale is a liquidity event. Thus, owners who truly intend on cashing out of their business would be well advised to pursue the sale of their company as opposed to an IPO.

Selling a company has fewer regulatory complexities and an accelerated timeline when compared with an IPO. An investment bank can help the company find the right buyer and structure the deal in the owner’s favor. For example, if the business owner is keen on receiving immediate compensation in the form of cash from a buyer, the M&A advisor can structure the deal in this fashion. In this way, a business owner can cut ties with the company upon closing a deal. On the other hand, the business owner can be awarded stock in the new company if he or she would like a continued interest in the success of the newly merged company. An M&A event provides flexibility with regard to the business owner’s future. Most importantly, however, M&A can be less costly and achieved more quickly than an IPO.

In contrast, an IPO fundamentally transforms a company from a private entity to a public one. There are numerous downsides and costs associated with this process of going public. First, there are some direct fees to execute an IPO: underwriter, legal, accounting, printing, and roadshow costs. Furthermore, the business owner is often required to retain his or her shares in the newly public company for a certain amount of time, referred to as a “lock-up period.” This precludes the owner from cashing out of the business right when the IPO is completed.

Following the IPO, the company incurs additional expenses to comply with the stiffer rules and regulations of a public company. For example, newly public companies often need to add employees to meet SEC financial reporting regulations and to comply with Sarbanes-Oxley. In short, an IPO requires more planning, preparation, and expenses than a company sale. Thus, a business owner can most effectively and efficiently cash out of his or her business through a sales transaction rather than an IPO. Furthermore, once the business owner cashes out, he or she can diversify their investments. This is certainly not possible with an IPO where the business owner is, essentially, trading private shares for public shares.

Thus, to answer why Versailles Group recommends M&A versus an IPO, it’s relatively simple to see the advantages of a company sale over an IPO. Perhaps the one big exception is where the owner sees tremendous growth and is willing to “suffer” a huge amount of dilution because the company is going to “explode.” The downside, of course, is that once a company is public, there is a large amount of pressure, every quarter, to show increasing revenues and profits.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

Jun 11

Why Business Value Calculators Fall Short: The Case for Investment Banks

Donald Grava June 11, 2015

The Problem With Business Value Calculators (And Why You Should Hire An Investment Bank Instead)

If you’re a business owner interested in selling your company, it’s likely you’ll be tempted to use online tools such as Business Value Calculators to help you figure out where to start. However, using these business value calculators can often be risky - these tools frequently provide misleading or outright inaccurate data that can seriously jeopardize your prospects for a successful sale.

The issues with business value calculators are numerous. At their essence, they lack the complexity of real life. In an actual M&A transaction, the final price that a seller receives depends on a multitude of multifaceted factors, including (but not limited to) the sellers financial statements, the condition of the seller’s company, industry conditions, macroeconomic market conditions, and perhaps most significantly, the preferences of the buyer.

As the adage goes, “garbage in, garbage out.” Business value calculators are designed to be quick and easy tools that anybody can use, meaning that they avoid complex and difficult data. But without sophisticated data, these calculators can’t give you sophisticated results. Instead, most calculators simply ask for your company’s industry and its EBITDA (earnings before interest, taxes, depreciation, and amortization. (EBITDA is, oftentimes, used as an approximation of cash flow.) With that minimal data, the business value calculator quickly makes an educated guess based on industry averages. Unfortunately, this method is only accurate if you happen to be selling the most average firm in the world, to the most average buyer in the world, during the most average economic conditions in world history. Therefore, in almost all cases, the results of business value calculators will only mislead you either into a false sense of security due to overvaluation or into a false sense of defeat due to undervaluation.

To be fair, business value calculators can be useful if you run a particularly small business (e.g., less than US$5 million in annual revenue), where minor differences in valuation are just that, minor. If your business is larger, a minor undervaluation could mean that you’ll lose a million or more dollars. In fact, it’s exactly in these sorts of situations that you may want to consider hiring an M&A advisory firm. Even for small business owners, representation by a boutique investment bank means that you’ll receive an accurate valuation for your company and therefore be in the strongest possible position when price negotiations begin with potential buyers. The investment bank will also know how to push the valuation to its maximum.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

Jun 09

How To Sell A Business For Maximum Value

Donald Grava June 9, 2015

How To Sell A Business For Maximum Value

Every business owner wants to know how to sell a business for maximum value. Perhaps the first step is to understand the most important metric that a buyer will use in valuing your company.

All entrepreneurs interested in selling their company will hear the acronym “EBITDA” (short for “earnings before interest, taxes, depreciation, and amortization”) being tossed around. EBITDA is a popular valuation metric that is usually calculated to approximate a company’s “free cash flow.” To find your company’s EBITDA, all you need to do is take its net income, then add back interest, taxes, depreciation, and amortization.

If you’re selling your company, however, you should be wary about over-relying on EBITDA calculations to determine the value of your company. While popular multiples such as Enterprise Value divided by EBITDA can provide basic insights into the relative value of your company, at the end of the day, such multiples are never the be-all, end-all of valuation.

The EBITDA metric itself has many shortcomings and limitations. Sophisticated buyers are acutely aware of these issues and it’s the major reason why entrepreneurs sometimes have trouble understanding why a professional buyer will place a lower value on their company than the simple EBITDA times a multiple that the entrepreneur used.
Professional or sophisticated buyers prefer to value a company based off its true free cash flow, which represents the amount of cash a company produces that is immediately available to shareholders and debtholders.

While EBITDA is often compared to “free cash flow,” in reality, the two metrics are actually calculated somewhat differently (both are based on EBIT, or earnings before interest and taxes). To recap,

EBITDA = EBIT + Depreciation + Amortization

whereas,

Free Cash Flow = EBIT * (1 – tax rate) + Depreciation + Amortization – Changes in Working Capital – Capital Expenditures

As you will note, there are three main differences between the metrics: Free Cash Flow includes
Taxes
Changes in working capital
Capital Expenditures

Taxes, working capital, and capital expenditures are important to the well-being of a company, yet EBITDA completely ignores these items. This is the fundamental problem. EBITDA is only an accounting metric, which cannot accurately represent how much free cash flow your company actually produces. And it’s true free cash flow that drives the value for your company. Sophisticated or professional buyers aren’t seeking a return on their investment in EBITDA; they want it in cash or free cash flow.

Thus, an entrepreneur who is interested in selling a business for maximum value should recognize the difference between EBITDA and true free cash flow. For many businesses, these two numbers are completely different.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

Jun 04

Maximizing Value When Selling: Payment Options Beyond Cash

Donald Grava June 4, 2015

How to maximize value when selling

The Seller’s Perspective: Is Cash Really King?

If you’re selling your company, one of the most important things to consider is the method of payment. Will you receive cash, debt, stock, or other consideration? That is, literally, the multimillion-dollar question.

Most business owners prefer to receive cash, at least initially. As they say, “cash is king.” It’s simple, easy, and it gives owners a sense of closure that no other alternative can offer. Yet in many transactions, cash isn’t always a feasible option, or even necessarily the best option. Instead, business owners should always consider legitimate alternatives to cash, such as debt, stock, and contingent payments. The seller, with his M&A advisor, should weigh the respective pros and cons of each appropriately. Below is a brief overview of these options:

Cash

Sometimes, an all-cash payment will make the most sense for the seller. If you don’t trust in your buyer’s long-term stability, solubility or ability to run the merged company, then “taking the cash and running” may really be your best bet, regardless of whether or not the buyer offers you a better deal. Nobody wants to be paid in debt, stock or other contingent payments when all it gives you is a stake in a “sinking ship.”

Getting paid in cash is also a good idea if you’re in a hurry to completely divest from your current company or industry. Cash can offer you a fresh start and an ability to diversify your wealth. This would not be true of a stock, debt, or contingent payment deal.

Sometimes, the decision to choose cash as payment isn’t necessarily so simple. If the economy is weak, it may be difficult for the buyer to generate cash. And even in a good economy, a buyer still might give you a better deal if you accept some part of the consideration in debt, stock, or other contingent payments.

Alternative #1: Debt

If your buyer has good credit and you can get a higher valuation, you should strongly consider accepting some debt (usually in the form of promissory notes) as payment. This may also enable a buyer that you’d like to work with in the future to complete a transaction even though they didn’t have enough cash to close the transaction. If the credit is good, then even with debt, you’ll eventually be paid the same amount in the end—or possibly even more, depending on the interest rate. In some cases, you may actually find that buyers are willing to pay more for your company if you’ll accept debt. When it’s easier for buyers to finance, after all, it’s also easier for buyers to pay a higher price.

Of course, debt carries its fair share of disadvantages. For starters, it’s riskier than cash, since you’ll likely be counted as a subordinated lender. That means that if your buyer goes bankrupt, you’ll only be able to reclaim your money after other, more “senior” lenders have already taken their share. And unlike cash, you won’t be receiving all of your money up front, since the debt will be paid off over time, usually two to five years.

Alternative #2: Stock

In other instances, the buyer may offer you their stock as payment. Frequently, this is offered in addition to cash or debt. Buyers often do this when they want to keep you involved with your company, even after you sell it. If you trust the long-term prospects of your buyer, accepting a stock payment can very easily become the most lucrative option of all. You can often receive a better deal from buyers if you accept stock instead of cash, and unlike debt, the theoretical rate of return on a stock is limitless. Many times, a seller makes a very hefty return on future increases in the stock price.

Obviously, this option isn’t ideal for those who want to make a clean break from their businesses and retire from the industry altogether. Stock is also riskier than cash or even debt. If the buyer goes bankrupt, stockholders are the very last in line to get their money back.

Alternative #3: Convertible (Debt) Securities

Convertible debt securities aim to combine many of the upsides of debt and stock payments, with none of the downsides. Essentially, a convertible debt security is a piece of debt (often a bond) that can be optionally converted into stock at a given “conversion price.” If you don’t want to choose between debt payments and stock payments when selling your company, payment via convertible debt securities may be a good solution. You receive the aforementioned benefits of debt, including regular interest payments and more bankruptcy protection, while also gaining the benefits of stock, such as the ability to share in the buyer’s future profits (if you convert your security).

Nevertheless, convertible securities are not without disadvantages. They tend to offer lower interest rates than regular debt, and their conversion price is usually set well above the current market price of the buyer’s stock at the time of transaction. To summarize, if you’re lucky, compared to stock, convertible securities will give you equivalent returns with lower risk. If you’re unlucky, then compared to debt, convertible securities will give you lower returns with equivalent risk.

Alternative #4: Contingent Payments

The most common contingent payment is the traditional earnout. Essentially, the seller will pay these amounts based on the future performance of the company. Most of the time, these arrangements are for relatively short periods of time, i.e., 12 to 36 months. This form of payment works best when the seller stays with the business and has the ability to influence the outcome.

There are as many forms of other types of contingent payments as people have the imagination to think them up. Versailles Group was involved in a transaction where part of the seller’s consideration was an annual payment of $1 million for the rest of his life. Provided that the seller, his investment banker, and lawyer analyze these alternatives thoroughly, they can be very rewarding for the seller.

Conclusion

At Versailles Group, we strive to keep our clients fully informed of all possible options during an M&A transaction, especially on the all-important matter of payment methods. That’s how to maximize value when selling. Our best interest is served when our client’s best interest is protected. Since 1987, this fundamental value has constantly reaffirmed Versailles Group’s position as a leading M&A advisor to middle market companies around the world. If you’re interested in selling or buying a business, please contact us for a free consultation.

May 28

Essential Elements of Effective M&A NDAs for Selling Your Company

Donald Grava May 28, 2015

How do I sell my company - NDAs

Many people ask us, how do I sell my company? There are many critical steps in that process; however, perhaps the most important one is a good Non-Disclosure Agreement. Most companies have Non-Disclosure Agreements or NDAs in order to share information with potential suppliers or other “partners.” However, most do not have a good M&A NDA. M&A NDAs are more specialized and cover some important items.

Before we explore what should be included in a good M&A NDA, it’s important to understand why this document is needed. The simple answer is obvious; the Company doesn’t want its data used for anything other than the exploration of a possible transaction. The less obvious reason is that the NDA is also for the benefit of the ultimate buyer. At the end of the day, the acquirer will have to face competitors and other buyers that just had a very detailed and in-depth look into the company being sold.

A good M&A NDA should cover the simple fact that none of the information revealed in the M&A process can be used for any purpose other than evaluating a potential transaction. It should also restrict the buyer from talking with customers, suppliers, employees, etc. Another important function of the NDA is to prevent potential buyers from hiring any of the employees, particularly the executives. This document should also prohibit the buyer from discussing the transaction with anyone other than the company’s advisors. It should be clear that any data shared with these other individuals is the responsibility of the buyer.

Some M&A NDAs also cover things like reps and warranties surrounding the preliminary information that is conveyed. It may also specify that the seller will cover the cost of its M&A advisor and that the buyer’s costs of exploring the transaction will remain its responsibility.

From a seller’s perspective, the NDA should provide a reasonable layer of comfort. From a buyer’s perspective, the NDA shouldn’t be so restrictive that they don’t want to even look at the company for sale. Many buyers who are afraid of liability problems will only look at non-confidential data before proceeding. This can be detrimental to the seller’s goal of generating the highest possible bid and the best terms.

As they say, “good fences make good neighbors.” Yet, it’s important for the document to have a balance between buyer and seller. Experienced M&A advisors know what to look for in an NDA. It is important that all parties consult an attorney before executing an NDA.

With a proper M&A NDA, a seller will have taken an important step in answering the complex question of how to sell my company - NDAs.

May 26

How to Sell a Private Company

Donald Grava May 26, 2015


how to sell a company

Many company owners wonder how to sell their company. It’s a good question, and certainly every business owner thinks about this topic periodically. In our mind, it’s not only a question of how to sell their company; it’s how to sell it for the maximum value and best terms.

The actual process is not that complicated, but there are many pitfalls. Many owners think that they know who the most logical buyer will be when the time comes. But they’re always disappointed later when that buyer isn’t interested or makes an impossibly low offer. The other major mistake that’s made is to share information without a Non-Disclosure Agreement.

Versailles Group has handled a number of engagements where the owners had started the process themselves and then realized the problematic nature of that. Most business owners don’t have the time to devote to developing the buyer list, creating the materials that need to be shown, or dealing with the demands of the buyers. However, what has been even more astounding is to learn that these normally careful business owners have shared sensitive company information without any protection.

When selling, the most important thing is to have a Non-Disclosure Agreement (“NDA”) with the buyer. It’s always best to have an M&A NDA, which is different than a standard agreement. While a standard agreement may protect the information, there are many other items that should be included.

Beyond the NDA, the seller should have a strong list of potential buyers. An experienced M&A advisor or investment bank will know how to assemble a list of this kind. A good list will go well beyond competitors and known companies in the seller’s market. Versailles Group has sold a number of businesses to buyers that would be well beyond the normal lists created by others. We view the world as our territory, and we look for buyers that may be slightly outside of our clients' business. This creates additional demand, and these “other” buyers frequently pay more because they need access to the market, the products, the technology, etc.

A strong buyer is one of the key ingredients. The other is clear documentation that shows all of the USPs or Unique Selling Points of the company. An M&A advisor will know what buyers are looking for in this type of presentation and know when and how to convey it. This is an art that is developed over the course of many transactions and many years of experience.
Once the buyers have the appropriate information, and if there are multiple buyers, an auction can be created. This is a silent auction and totally confidential. It enables the seller to derive extra value or enhanced terms from the transaction. Offers are usually stated by the buyer in terms of a Letter of Intent.

Once the Letter of Intent is executed, the buyer will conduct thorough due diligence. A good M&A advisor will be able to help their client manage this process. At some point, the buyer will produce a Definitive Agreement. Sellers should pay close attention to the terms and conditions, particularly the representations and warranties. This is a critical document in the process. Versailles Group, as a result of its years of experience, knows what should and should not be in a document of this type. It’s also important to know how to negotiate these documents. That’s critical!

Most transactions are a simultaneous sign and close, and that will be the day that the consideration is conveyed to the seller. If done properly, it’s a happy day for both parties.

May 14

Operational Due Diligence in M&A Transactions

Donald Grava May 14, 2015
Operational Due Diligence


Due diligence is an important aspect of all M&A transactions as it is a process that allows the acquirer to truly understand what they are purchasing. Mistakes during this process can prove to be costly and can make the difference between a successful acquisition and a failed one. The most common mistakes acquirers make during this process are failing to conduct operational due diligence and utilizing inexperienced people to conduct the process in an effort to save on costs.

When conducting due diligence, most buyers tend to focus their efforts on financial, legal, and Human Resource due diligence. What is all too commonly missed during this process is the operational due diligence, i.e., studying, in detail, the customers, products, services, and business pipeline of the company to be acquired.

Most of the time, acquirers in the same industry don’t focus on operational due diligence as they feel they already understand the target’s business or customers. In reality, it is extremely difficult to truly “know” a company as every business is unique and competitors within the same industry will usually attempt to conceal their operations from one another. Operational due diligence should not only consist of asking customers about their satisfaction levels with the target company, but also thoroughly examining customer contracts to fully understand the risks involved with acquiring those customers.

Another common mistake acquirers make is using inexperienced people to conduct the due diligence process in an effort to save costs in the short term. This strategy can lead to substantial losses in the future as inadequate due diligence increases the likelihood of missing important red flags. Acquirers should always utilize employees who are qualified to conduct thorough due diligence. If such employees do not have the bandwidth to conduct the process or will slow down the transaction to a great degree, then the acquirer should always consider hiring a consultant who knows the industry and has experience performing M&A due diligence. While using more senior employees and hiring outside consultants will increase the cost of the transaction, this is certainly money well spent to ensure that the acquisition will be valuable to the acquirer.

It is all too easy for acquirers to feel comfortable with targets in their industry. However, acquirers cannot afford to overlook operational due diligence and must treat every acquisition as a prudent investor. It is also imperative that acquirers are not “penny wise and pound foolish” in the performance of due diligence. Utilizing experienced employees and hiring outside consultants to conduct the due diligence process may increase the cost of the acquisition, but it will ensure the acquisition adds to shareholder value.

Acquirers should always ask their M&A advisor how to organize their diligence. M&A advisors cannot perform the actual diligence as they have a conflict of interest. However, most well-experienced M&A firms have seen the diligence efforts from both sides of a transaction. Consequently, they have the unique ability to help organize the efforts and to avoid common pitfalls, particularly with neglecting operational due diligence.

Versailles Group, a boutique M&A firm with decades of experience in helping buyers and sellers, knows how to guide a client through this very important process. They have seen, first hand, how to and how not to conduct proper due diligence.

May 05

Why Conduct Due Diligence?

Donald Grava May 5, 2015

Why Conduct Due Diligence?

Many buyers ask, why conduct due diligence?

Due diligence is an audit of a potential M&A investment, which takes place prior to the closing of a transaction. Due diligence plays an important role in every M&A transaction. It is a discovery process that helps buyers understand the financial statements, potential synergies, cultural differences between the companies, and possible risks of a particular target.

Financial Diligence

It’s imperative for a buyer to conduct thorough due diligence on the target company’s financial records, particularly the income statement and balance sheet. A buyer needs to test the income statement to make sure that revenues are not inflated and that expenses are not understated. Similarly, the balance sheet items, or the value related to said items needs to be verified. In many cases, a buyer will test the inventory or even do a complete physical inventory to determine if it has been corrected stated on the balance sheet. In many cases, a buyer will also conduct a “quality of earnings” examination to determine if the earnings of the company match their understanding. Last, but not least, the buyer will want to make sure that they understand the cash flow of the business. This goes well beyond EBITDA!

Evaluating Potential Synergies

Synergies are the main motivators for many M&A transactions. Generating returns above and beyond what the two companies could achieve as separate entities is usually the goal of an acquirer. One of the most common pitfalls of M&A transactions is overestimating possible synergies. This results in buyers overpaying for target companies and, in many cases, a failed acquisition. The due diligence process is a chance for buyers to do their “homework” on a target to see if these potential synergies can be realized. While potential synergies with a target company can be very appealing, it takes thorough due diligence to develop a roadmap to take these synergies from theory to reality.

Understanding Company Culture

Understanding a target’s company culture can be the difference between a successful acquisition and a failed one. In most cases, a company’s greatest asset is its employees, as these are the people who manage the day-to-day operations and develop the strategies that define a company. The employees are a vital asset that is going to be acquired, and a potential buyer should take the time during the due diligence phase to understand the culture. The culture in the workplace is one of the critical factors in determining the success of an acquisition. Differences in company culture are not always a negative, as the two cultures can learn from one another; however, cultures that are radically different and cannot be managed properly will create a toxic work environment that destroys value. Due diligence gives the acquirer a chance to evaluate a target’s employees and will give the acquirer a better sense of whether these employees can be successfully integrated.

Discovering Potential Risks

Due diligence gives the buyer assurance that it is not assuming undue risk by acquiring a target company. Before signing a definitive agreement, every acquirer should have a full understanding of the risks that an acquisition poses. From a legal standpoint, the buyer will use due diligence to understand any potential litigation the target company could face in the future and if the acquirer could be liable for any damages resulting from that litigation. Due diligence also gives buyers insight into the operational or financial risks of an acquisition. Debt covenants, supplier contracts, integration costs, possible off-balance sheet liabilities, etc., should all be thoroughly examined before committing valuable resources to purchasing a company.

Conclusion

Acquisitions are essential to almost every corporate strategy. They can be an effective way of building shareholder value and saving companies time when trying to break into new geographies or product lines. Due diligence is an opportunity for acquirers to obtain a better understanding of the potential returns and risks of an acquisition. If utilized properly, due diligence can ensure the completion of a successful acquisition.
While there are conflicts that prevent your M&A advisor from actually completing the due diligence, a good financial advisor should be able to advise their client on how to conduct the diligence process, what to expect from the process, and how to mitigate the risk of any negative findings by making adjustments to the Purchase and Sale Agreement. Versailles Group has decades of experience in advising both buyers and sellers in executing successful transactions.

Apr 02

M&A Deals: Sell-Side Considerations for Middle Market Business Owners

Donald Grava April 2, 2015

For an owner of a middle-market private company, hiring an experienced boutique investment bank is crucial when considering the sale of your business.  Professional M&A advisors with decades of transaction experience not only help determine your company's true market value but also implement strategies to maximize that value throughout the sales process.  Just as importantly, the right advisor helps secure favorable terms, which is often overlooked when sellers focus solely on price.  In reality, a successful M&A transaction involves far more than valuation alone. 

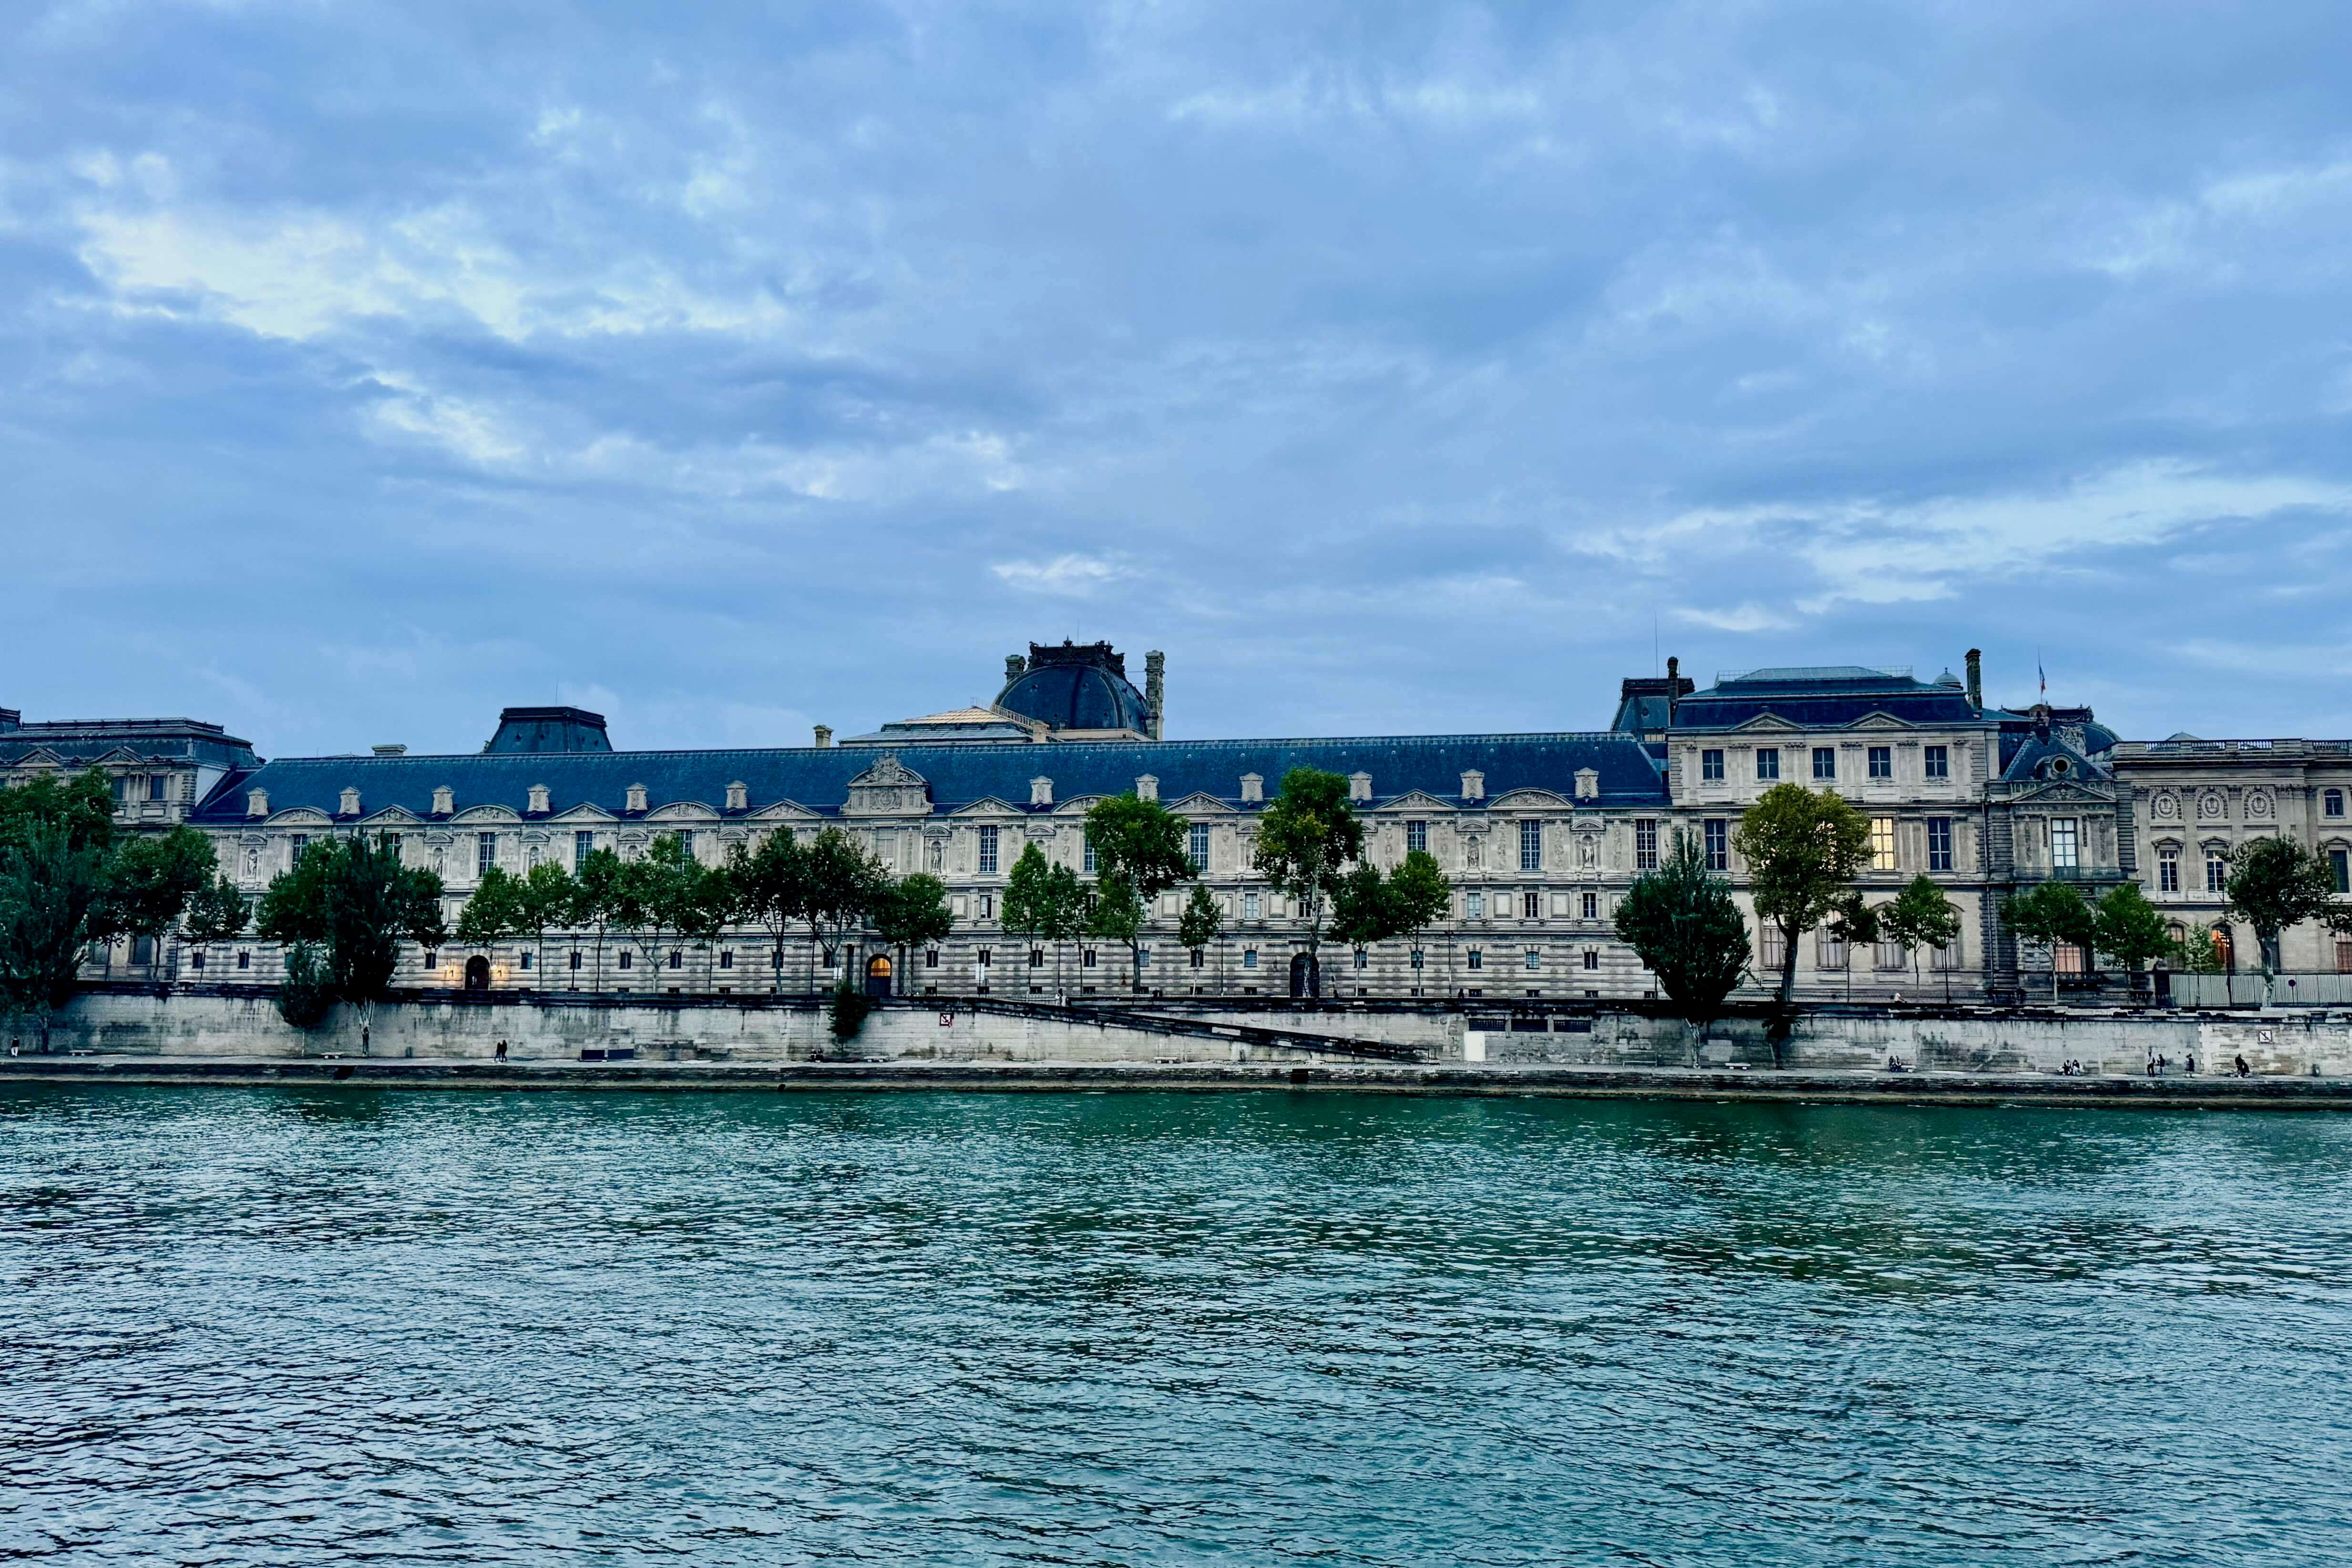
View of Paris, France

Considerations Before A Sale

Optimal Timing for Your Exit

One of the most critical decisions entrepreneurs face is determining when to sell their business.  Many make the mistake of delaying a sale to implement "one more improvement," such as launching a new product line or developing an additional sales channel.  While these initiatives may seem beneficial, they often cause owners to miss peak market conditions, overlook emerging competitive threats that could reduce value, or delay unnecessarily as industry dynamics shift.

Another common mindset we have seen is anticipating another year of strong growth, prompting owners to miss the optimal window to sell.  Markets fluctuate, regulations change, and personal circumstances can unexpectedly force a sale under significantly less favorable terms.

The best exits occur when your business is performing well and you can sell from a position of strength, not under external pressure.  It’s important to hire an M&A advisor who will analyze market trends, industry consolidation patterns, and your company's growth trajectory to identify the optimal selling window before value deterioration occurs.  In other words, taking a proactive approach enables you to control both the timing and the narrative presented to buyers.  

Preparation For Sale

Another important point to consider is preparing the company for sale.  Some of the items that should be included are: organize financial records and clear up any issues with customers, employees, suppliers, etc., streamline operations and reduce owner dependence.  Most importantly, the potential seller should resolve any legal and compliance issues that are outstanding.

Confidentiality Protection

Business owners should carefully consider how confidentiality will be maintained during the sales process, as it is critical to preserving business value.  An experienced M&A advisor can help by putting robust non-disclosure agreements in place, preparing anonymized marketing materials to protect your identity in the early stages, and using a strategic approach to buyer outreach that minimizes competitive risks while maximizing value and favorable terms.

Market Approach Strategy

You'll need to determine whether a broad marketing approach (contacting numerous potential buyers) or a targeted approach (approaching select strategic acquirers) best serves your objectives.  This decision should weigh the likelihood of achieving maximum valuation through competitive tension, industry-specific confidentiality concerns, the strategic fit with specific buyers who might pay premium valuations, and timeline considerations.  Included in this analysis will be management bandwidth constraints.  A good M&A advisor can help weigh the pros and cons of the various approaches.


Considerations During A Sale

Preparation for Buyer Meetings

Before buyer engagement begins, your M&A advisor should help you anticipate likely buyer concerns and prepare detailed responses, address potential red flags with appropriate context and remediation plans, and maintain operational focus.  Being thoroughly prepared to address questions about operations, technology, human resources, and financials is essential for maintaining deal momentum and credibility.  Building credibility with the buyers is essential to achieving a successful outcome.

Negotiation Strategy

Expert negotiation is critical to maximizing value beyond just the headline purchase price.  Key considerations include purchase agreement structure and terms, working capital adjustments, earnout provisions and their achievability, representation and warranty terms, non-compete provisions and their scope, and post-closing operational requirements.  Each of these elements can significantly impact the final value you receive from the transaction and should be carefully negotiated with professional guidance.  In this regard, your M&A advisor will team up with your attorney to not only protect your interests but also to maximize the valuation and contractual terms.

Exclusivity Period

Once a buyer submits a strong offer and you move into due diligence, they will typically request an exclusivity period (also known as a “no-shop” provision).  During this period, which usually lasts between 30 and 90 days, you agree not to negotiate with other potential buyers while the buyer conducts a thorough review of your business.

Exclusivity is a standard part of M&A transactions, but it does shift negotiating leverage toward the buyer.  For that reason, it should only be granted once a buyer has demonstrated real commitment via their actions and through a strong purchase price and favorable terms.  It is also important to negotiate a reasonable time frame and to keep the process moving efficiently with a well-prepared data room and responsive communication.

When managed properly, the exclusivity period can create focus and efficiency, helping both parties progress toward closing.  When handled poorly, it can result in wasted time, reduced negotiating power, and missed opportunities with other interested buyers.


Considerations After A Sale

Integration Planning

After completing the M&A transaction, focus shifts to integration and operational continuity.  Even when departing, sellers play a vital role in facilitating smooth leadership transitions, helping retain key employees through the change, ensuring customer relationships remain stable, and preserving the company culture that's been built over time.  A thoughtful transition preserves the entrepreneurial legacy while positioning the company for continued success under new ownership.

Legacy Protection

Your M&A advisor should help you develop appropriate transition strategies that protect the interests of loyal employees, maintain quality standards for longtime customers, honor commitments to business partners and community stakeholders, and safeguard the reputation you've worked decades to build.


Conclusion

In summary, selling your business represents the culmination of years of entrepreneurial effort. Working with experienced M&A advisors who understand the nature of transactions provides the expertise needed to navigate this complex process successfully.

For expert guidance on middle-market M&A transactions, please contact our experienced team of investment bankers who would be happy to discuss your objectives on a confidential basis. Such consultation will be performed at no cost to you.


Written by Donald Grava

Originally published:  29 Jul 2015

Last updated:  21 August 2025


Versailles Group, Ltd.

Founded in 1987, Versailles Group is a boutique investment bank that specializes in international mergers, acquisitions, and divestitures. Versailles Group’s skill, flexibility, and experience have enabled it to successfully close M&A transactions for companies in the middle and lower-middle market. Versailles Group has closed transactions in all economic environments, literally around the world.

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

Mar 26

When a Good Deal Goes Wrong: Why Middle-Market Acquisitions Fail

Donald Grava March 26, 2015

M&A Deals - Failed Acquisitions

M&A Deals - Failed Acquisitions

Many acquisitions look compelling at the time they are announced. The strategic rationale is clear, the financial model supports the transaction, and both buyer and seller have reason to believe the combination will create value.

Yet some M&A deals fail to deliver the expected result.

In lower middle-market and middle-market transactions, failure is often not the result of a single mistake. It is more commonly the result of assumptions that were too optimistic, diligence that did not go deep enough, transition risks that were underestimated, or management and cultural issues that became more difficult after closing.

After the closing of an M&A deal, it is up to the buyer to ensure the success of the transaction. However, not all of the work comes after closing. In fact, the most successful buyers expend significant time and effort before closing to understand the business, assess the risks, and develop a realistic plan for ownership.

Overestimating Synergies

When the buyer is overly optimistic about possible synergies with the target company and potential economies of scale, it can lead to disappointment after closing. Buyers may expect cost savings, cross-selling opportunities, revenue growth, purchasing efficiencies, or broader market access. Those opportunities may be real, but they must be tested carefully.

If the newly acquired company’s products or services do not grow as anticipated, or if customers do not respond as expected, the acquisition can fall short of its intended objectives. Similarly, if the buyer has underestimated the strength of market competition, the amount of capital needed to grow the business, or other costs related to the transition of ownership, it can be difficult to achieve the expected result.

Overestimating cost savings can create similar problems. Savings that appear straightforward in a financial model may be harder to realize in practice. Reductions in staffing, facilities, systems, vendors, or administrative costs can affect morale, customer service, or operational continuity. In a middle-market acquisition, the margin for error is often narrower than expected.

Underestimating the Transition

If the buyer is unable to properly manage the business, the likelihood of a failed acquisition increases significantly. The management team needs to have a strong understanding of the business being acquired, including its customers, employees, competitive position, operating processes, and working capital requirements.

The acquiring company also needs to make sure that it retains key management and other employees to ensure that operations run as planned. This is particularly important when the acquired company has long-standing customer relationships, specialized technical knowledge, or informal operating practices that are not fully captured in written procedures.

A buyer may acquire the assets, customer list, contracts, and financial history of a company. But if key people leave, customer relationships weaken, or operational knowledge is lost, the value of the acquisition can deteriorate quickly.

Transition planning should therefore begin before closing. Buyers should evaluate which employees are essential, how customer communication will be handled, what role the seller will play after closing, and whether the buyer has the internal resources to manage the company effectively.

Cultural and Management Issues

If the corporate cultures of the acquiring and acquired companies are vastly different, it can lead to poor chemistry between the employees of the two companies. This tension can deteriorate team effort, slow decision-making, and cause financial losses.

Culture is not always discussed with the same discipline as valuation, financing, or legal terms, but it can have a meaningful effect on whether an acquisition succeeds. A buyer with a highly structured corporate environment may have difficulty integrating a more entrepreneurial, founder-led company. Conversely, a decentralized buyer may underestimate the guidance and support that the acquired company needs after closing.

For sellers, this issue matters as well. Many owners care about more than price. They want to know that employees will be treated fairly, customers will continue to be served well, and the business they built will be positioned for long-term success. If part of the purchase price is tied to an earnout, seller note, rollover equity, or continued employment arrangement, the buyer’s ability to manage the company after closing becomes even more important.

The Role of Due Diligence

In order to complete a successful acquisition, thorough due diligence is an absolute must. Such diligence should include a complete assessment of the buyer’s own strengths and weaknesses, as well as a detailed analysis of the expected financial results.

Buyers should examine the target company’s financial performance, customer concentration, management depth, employee retention risk, competitive position, legal obligations, tax matters, working capital needs, and capital expenditure requirements. They should also consider whether their assumptions about synergies, growth, and integration are realistic.

Due diligence is not simply a process of confirming that the numbers are accurate. It is also a process of understanding how the business creates value, where that value may be vulnerable, and what must be done after closing to preserve and grow it.

While there are too many conflicts of interest to have an investment banker complete the buyer’s due diligence, experienced M&A advisors are well equipped to help guide the process. A well experienced investment banker knows the potential pitfalls related to doing an acquisition and can help buyers and sellers anticipate issues that may affect value, structure, timing, or certainty of closing.

Why Sellers Should Care

Although failed acquisitions are often discussed from the buyer’s perspective, sellers also have an interest in whether a transaction is likely to succeed. A buyer that has not done proper diligence may attempt to renegotiate terms, delay closing, request more seller financing, or create greater uncertainty during the process.

Sellers should therefore consider not only the headline purchase price, but also the buyer’s financial capacity, industry experience, integration plan, treatment of employees, and ability to close. The highest offer is not always the best offer if the buyer cannot complete the transaction or manage the business effectively after closing.

In many middle-market transactions, the seller remains involved for a period of time after closing. The quality of the buyer, the clarity of the transition plan, and the alignment between buyer and seller can have a direct effect on the outcome.

Reducing the Risk of Failure

M&A deals can be exhilarating for both the buyer and the seller, if done properly. But enthusiasm alone is not enough. A successful acquisition requires disciplined analysis, realistic assumptions, thoughtful diligence, strong communication, and a clear plan for the transition after closing.

The most successful buyers do not wait until after closing to think about integration, management, culture, or capital needs. They evaluate those issues before closing and structure the transaction accordingly.

For sellers, preparation is equally important. A company that is well prepared for diligence, supported by a strong management team, and able to present a clear growth story is more likely to attract qualified buyers and complete a successful transaction.

Versailles Group advises lower middle-market and middle-market clients on mergers, acquisitions, divestitures, private placements, and related transaction matters. If you are considering an acquisition, preparing to sell a business, or evaluating the risks associated with a potential transaction, please contact Versailles Group for a confidential consultation.