Jun 27

M&A Activity By Sector

Donald Grava June 27, 2014

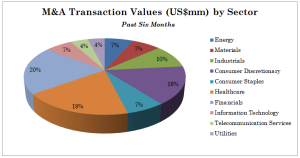
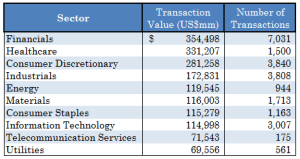
Worldwide M&A activity is continuing at a rapid pace this year for a number of reasons including the availability of credit, the robust liquidity of large companies and private equity firms, and the continued improvement in the economy.

By sector, Financials, Healthcare, and Consumer Discretionary transactions accounted for over half of the M&A transaction value. If one examines M&A transactions by the number of transactions, 66 percent of the transactions were completed in the Financial, Consumer Discretionary, and Industrials sectors.

The following pie chart and table show M&A activity by sector.


June-July Pie


June-July Chart


May 30

M&A Multiples On The Rise

Versailles Group May 30, 2014

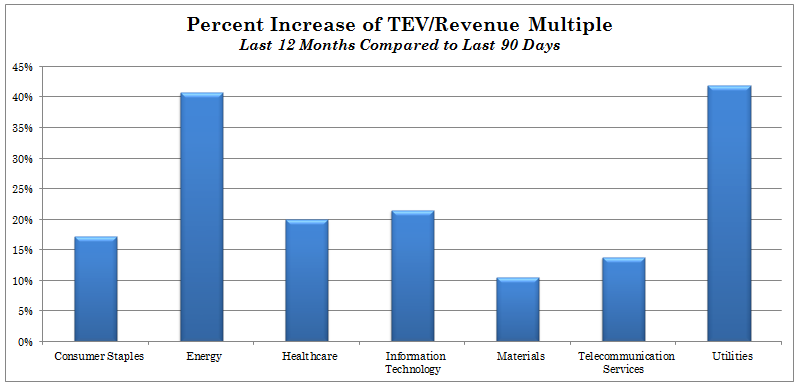
M&A activity was very strong in Q1; in fact, the M&A market this past quarter was more active than any quarter in the last several years. April and May continued this trend with a high level of activity in terms of both deal value and the number of transactions.

This heightened activity is driving multiples up as depicted in the chart below, which shows the percentage increase in TEV/Revenue multiples by industry from the last 12 months to the last 90 days.


May-june email blast chart


Why do deal multiples matter? If you’re a seller, you’ll receive more value for your company. If you’re a buyer, you’ll end up paying more. Therefore, it’s an opportune time for sellers to put their company on the market. Similarly, buyers should consider a transaction before the multiples increase further.


Mar 15

Building Shareholder Value Via Mergers and Acquisitions

Versailles Group March 15, 2014

With regard to building shareholder value, business owners and companies frequently ask themselves:

Is this the best time to sell my company or a part of my company?

Is this the best time to buy a company or part of a company?

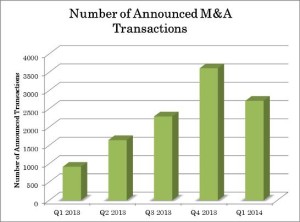
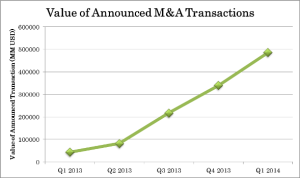
The charts below demonstrate from both a value perspective and the number of M&A transactions announced that now is the time to pursue these strategies.


March Blog3


March Blog1

The dramatic run-up of both deal value and number of transactions announced in Q1 2014 versus Q1 2013 is very evident, despite the fact there are still 15 working days left in March.

Jan 21

5 Questions to Ask in an M&A Software Transaction

Versailles Group January 21, 2014

m&a software transaction questions

Acquiring a software company is much like acquiring any company in that thorough due diligence needs to be conducted. That being said, there are five factors that are critical when examining a software company for acquisition.


M&A Software Transaction: 5 Questions to Ask

(1) Can the seller prove ownership of the source code? It’s important for the buyer to know that the source code is owned or was created by the seller.

(2) Will the software programmers that created the code stay with the company post acquisition? This is important, particularly with complex software programs as it’s difficult for outsiders to understand the architecture and features.

(3) Many times, sellers will offer their key employees, especially software programmers stay bonuses that match whatever time period the buyer is requesting. While that’s fine, many buyers have been quite surprised that after the magical time period that a majority of the employees leave. Therefore, it’s important for the buyer to know that any employee that has been offered a stay bonus may quit as soon as the time period is fulfilled. Such key employees may need additional incentives to stay beyond that bonus period. The best way to cover this is via a rep and warranty in the Definitive Agreement that reveals if stay bonuses are being paid and to whom.

(4) In any business, customers are critical as they provide the cash flow. The important question is how committed are they to the business being sold. If the customers are running important software programs and are worried that the new buyer won’t support them adequately, there might be a huge risk of them switching to another vendor.

(5) Another important point is to make sure that software license sales prior to closing don’t contain future obligations of updates or to maintain such software. That could be a very expensive obligation for a buyer.

Questions? Ask An Expert!
Jan 16

How to Vet Middle Market Investment Banks

Versailles Group January 16, 2014

If you’re considering hiring a middle market investment bank to either buy or sell a business, it’s important to check the firm out carefully. Successful transactions don’t just happen. To obtain the best result, transactions have to be managed carefully by seasoned professionals.
Photograph showing a magnifying glass placed on an open newspaper, focusing on a section about mortgages. The black-handled magnifying glass enlarges text beneath it.Middle market investment banks should have both domestic and international reach. That’s important for both buy and sell side transactions in M&A. On the buy side, one shouldn’t miss the chance to view every possible target in the defined geography. On the seller's side, it’s important that the seller not miss another possible buyer, who might have offered better terms and more consideration, just because they’re outside of the territory that is most familiar to a particular firm. In other words, one should hire a firm that can truly cover the world. There are always opportunities if one knows how to find them.

It’s also important for middle-market investment banks to have the ability to create excellent documentation. Those documents will be the first thing that the potential target or buyer will see about your company. As they say, “first impressions count.” If you take a moment to examine the documents that the prospective investment bank sent you, it’s a giant clue as to how they present their clients.

Another important element to check is the firm’s ability to structure and negotiate difficult transactions. The best way to ferret out this information is to ask about a complex transaction. Another way is to look at the firm’s “tombstones.” Are they all transactions between well-known buyers and sellers or are some of them cross-border and between companies that aren’t so obvious?

Staffing on any advisory engagement is important. How long have the principals of the firm been employed by that particular middle-market investment bank? What is their experience level? What are the chances that they will leave the firm mid-transaction? There have been many cases of clients being impressed with the individual handling their project, only to find that they took a better position across town. And, understandably, the transaction stays with the firm, not the individual. As we say, buyer beware.

To summarize, check out your middle market investment bank's experience level, years in business, credentials of the staff and ability to present well.

A little due diligence goes a long way to ensuring a successful transaction.


Speak Confidentially with Versailles Group

Versailles Group provides clients with both buy-side and sell-side M&A services and has been completing cross-border transactions since its founding in 1987.

If you are considering selling or acquiring a company, we welcome the opportunity to discuss your objectives and offer a clear perspective on your options.

Request a Session >>
Jan 07

3 Things to Know About Boutique Investment Banks

Versailles Group January 7, 2014

When hiring a boutique investment bank, it’s important to focus on three main areas:

How long has the firm been in business?

Often times, many boutique investment banks are in existence because the founder or founders are between positions at larger firms. Therefore, if the firm you are considering has been in business for less than five years, it begs the important question: Is this a part-time occupation or a serious business? Most sellers only have one company to sell, so it’s important that the advisor be serious and not in between lucrative positions. If the firm that you are considering has been in business for more than 10 or 20 years, you’re probably safe.

Boutique Investment Banks Things to Know

Who will work on the proposed transaction?

The staffing for the engagement is important. How much M&A experience do they have? How long have they been with the firm? Are they likely to leave the firm in the middle of your transaction? Experience is important as M&A transactions are never mundane. There are always twists and turns from all of the parties involved. A successful M&A transaction occurs when a series of challenges are solved fast enough to keep both buyer and seller engaged.

What are the capabilities of the boutique investment bank?

What types of deals has the firm completed to date? Do they have international capabilities, not necessarily international offices? In other words, have they completed cross-border transactions? Many firms claim to have that capability, but it’s limited to completing transactions to or from their home country. True cross border capabilities include the ability to complete transactions completely outside the firm’s home country. International capabilities are more important now than ever before. The world has gotten smaller and it’s expensive to miss opportunities just because they’re outside of your geography.

Questions? Ask An Expert!

photo credit: kenteegardin

Dec 24

Do I Need a Boutique Investment Bank?

Versailles Group December 24, 2013

Many buyers or sellers wonder if they need a boutique investment bank versus a large full service firm. If what you need is a successful M&A transaction, you’re typically better off with a firm that derives all or most of its revenue from M&A. That means you’ll receive the best and most attention.

Do I need a Boutique Investment Bank

Typically, boutique firms are more nimble and able to react faster than larger full service firms. Therefore, they’re much better at completing middle market transactions where the number of buyers or targets is quite large. Boutiques are adept at operating in this environment. Boutiques are also good at giving the entrepreneur or corporate client that hasn’t completed a number of transactions the necessary advice to “walk” them through a complex maze of finding the right buyer or seller, presenting the transaction, helping guide due diligence, structuring a transaction that will be mutually agreeable, and negotiating a Definitive Agreement. All of these steps involve lots of intricacies that need to be managed efficiently and effectively. To conclude, for most middle market transactions a boutique investment bank will probably provide the highest level of service and the best possible outcome for either a buy or sell side assignment.

Questions? Ask An Expert!
Dec 10

How Middle Market Investment Banking is Different

Versailles Group December 10, 2013

Middle market investment banking provides some unique challenges for both buyer and seller.

Most importantly, the number of buyers or sellers available to do a transaction, relative to the very large deals that dominate the headlines, is huge. Many people underestimate how many possible targets or buyers there are to complete their transaction. It’s one of the reasons why an M&A advisor is even more important for a middle market transaction.

middle market investment banking different

Another major distinction of middle market investment banking is that most of the entrepreneurs have never purchased or sold a business before. For many of these individuals, pursuing a transaction may be difficult to understand. M&A can be a complex maze. For example, it’s important how and when certain information is released, when and what type of Non-Disclosure Agreement is used, and how to structure a transaction that is fair to both parties.

The value of a middle market investment banking transaction is always a hot topic among both buyer and seller. Many entrepreneurs have devoted themselves to building their business so they’re not familiar with terms like EBITDA or multiples. There are many stories about this misunderstanding, for example, one entrepreneur was telling everyone that the EBITDA multiple was dictated by the company’s zip code. Nothing could be further from the truth, but this poignant comment is a clue that M&A is a highly specialized field. Another entrepreneur noted that they wanted to sell their business for x million based on his retirement needs, the necessity of paying for their grandchildren’s college educations, etc. Those were all admirable goals, but had nothing to do with the value of the business.

Negotiating a transaction is an art, not a science. To be successful, both parties, on either side of a transaction, need to focus on win-win negotiating. That usually produces the best outcome for both parties. As most middle market business owners do not have significant M&A negotiating experience, there are frequently many transactions that fail. Most of them could have had a positive outcome, but the parties did not find a solution fast enough to keep the transaction moving forward.

To summarize, middle market investment banking is different than very large company investment banking. First of all, most of the time, it’s the individuals’ own money that is at stake. Large companies have millions of shareholders and a mistake on an M&A transaction won’t carry the consequences of a bad transaction for an individual. In most cases, the success of a middle market transaction could be insured by engaging professional investment bankers who know how to navigate the complex M&A maze, can guide the negotiations, and have the requisite experience to structure a mutually acceptable transaction.

Questions? Ask An Expert!
Oct 16

Q3 Global M&A Activity

Versailles Group October 16, 2013

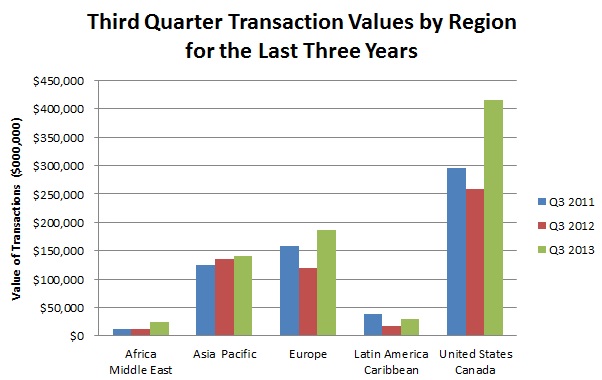
In the third quarter, M&A activity in the US and Canada increased dramatically, exceeding both 2012 and 2011 activity levels. Europe has also seen a resurgence of M&A activity despite some very difficult economic conditions. M&A activity is also up in Asia / Pacific, Africa / Middle East and in Latin America; however, Latin America hasn’t seen as much of an increase as the other geographies.


Versailles Group Blog August 2013

The question that this raises is why is M&A activity increasing? There are many reasons for this, including strong fundamentals, e.g., cheap and available capital, but also the simple fact that companies find M&A to be a very attractive way to build or defend shareholder value. Clearly, it’s faster and more advantageous for a company to acquire another business, people, products, equipment, customers, etc. than to build it from scratch. That’s an opportunity for both buyer and seller.

The fourth quarter is an excellent time to begin exploring the acquisition or divestiture of a business to build or protect shareholder wealth in the coming year. I founded Versailles Group almost 27 years ago as I’m passionate about helping management and/or owners grow or divest their businesses to enhance shareholder wealth.

Sep 18

Global M&A Activity

Versailles Group September 18, 2013

Year-to-date, M&A activity has been robust, as reflected in the chart below. Despite a modest start to the year, the value of M&A transactions is up, over the same time period last year, in all regions except for Asia Pacific.


Versailles Group Blog August 2013

Low interest rates, willing lenders, buyers with large cash balances, and other strong fundamentals are contributing to M&A activity around the world. And, it appears that deal multiples are increasing due to competition between private equity firms and strategic buyers. One of the strategies of both of these types of buyers is to enhance shareholders’ wealth via the acquisition of companies.

There are two questions that every business owner or CEO should ask, at least annually: when should we acquire a company and when should we sell either all or part of the company. The answer is not always straightforward, but the question is worthy of significant attention. With over 30 years of M&A experience, I have personally seen many businesses miss valuable opportunities by hesitating to consider a transaction.